l
l
blogger better. Powered by Blogger.

Search

Labels

blogger better

Followers

Blog Archive

Total Pageviews

Labels

Download

Blogroll

Featured 1

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 2

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 3

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 4

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 5

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Wednesday, June 6, 2018

Order-ahead app Ritual picks up $70M to rethink the social office lunch break

While DoorDash, Postmates and other apps are looking to reimagine what the food delivery experience looks like, Ray Reddy says he wants to figure out what the next generation of a food court looks like. Sort of.

Reddy’s startup, Ritual, aims to remake the whole process of leaving your office and walking around five minutes to a nearby deli or cafe to pick up food for lunch. But Reddy and his founders Larry Stinson and Robert Kim wanted to focus first on getting that experience right for a single building that leaves to go pick up coffee or food — and has that daily ritual of getting lunch with the team, or something along those lines. The whole process boils down to an app for consumers to order food or drinks as well as have coworkers piggyback onto that order to create a more socialized experience around getting up and going around the corner for a snack. Ritual said it has raised a new $70 million round led by Georgian Partners, with existing investors Greylock Partners, Insight Ventures, and Mistral Venture Partners all participating.

“If we [couldn’t] build something that is compelling for the 300 people who work at this single building, it’s not gonna work period,” Redddy said. “That helped us define the problem narrowly. We thought, here are the 12 or 14 spots within a five minute walk of this building, let’s focus on simulating what would happen. Let’s not worry about financials or economics, let’s prove this works. Just like Uber’s a remote control for the real world, we viewed this in a similar way where ultimately the app is a remote control for a real world experience.”

Ritual’s main flow is probably something the typical user is accustomed to at this point when it comes to food. They pick a place they like, place an order for food (or coffee), and then go pick it up. But the whole background process involves not only getting restaurants on board with the specific things they want while still trying to calibrate a consistent experience that users at this point expect when it comes to ordering something online after being trained on that simplicity for years by Postmates, DoorDash, or even apps by companies like Starbucks.

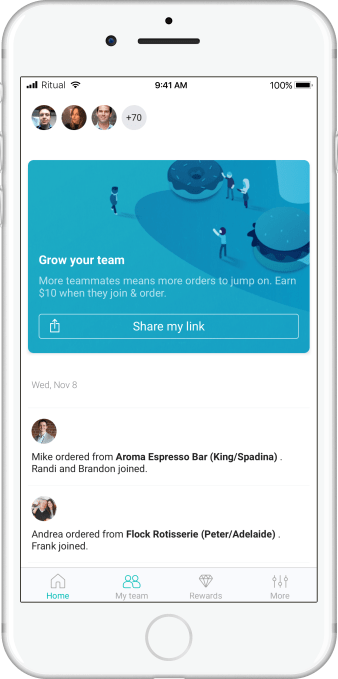
But over the past year or so, the company has increasingly tuned itself to employees jumping aboard the same order when considering what to pick up for a snack or a meal. The whole process aims at emulating that experience of figuring out where you want to eat in a Slack channel or arguing over a Seamless order, and in the end whoever has time to run out and grab something will be able to bring things back for teammates (or, of course, everyone can leave at the same time). That whole process is called “piggybacking,” a feature the company introduced around 18 months ago. The company has around 44,500 teams using the app, Reddy said.
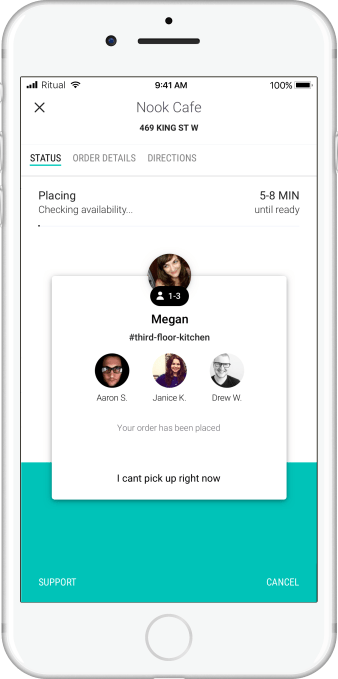
 

All this is aimed to help restaurants adapt to the same changes in user behavior that retail has seen in the past decade, Reddy said. Amazon trained users to buy things online, forcing retailers to shift their strategies, just as Postmates and DoorDash have trained users to order food delivery through apps and immediately have access to a ton of options. With all that comes more and more data, which has helped those industries slowly tune their models over time and try to keep up with the increase in demand that has come with reducing friction around the whole experience.

“What restaurants are seeing are right now the same challenges retailers saw 10 years ago,” Reddy said. “What does it mean to become omni-channel, how do you go from one customer segment to dealing with walk-ins plus digital orders. Retailers faced a lot of those challenges 10 years ago, they faced challenges around pricing, fulfillment, and how do they build new capabilities. They are dealing with a new source of demand, and fundamentally the problem was a lot of stores weren’t designed for accepting multi-channel origins.”

While an order-ahead app might be one way to connect online users to a physical location, there’s still plenty of work to do as most restaurants, coffee shops or typical stores aren’t tuned for a digital-first experience, Reddy said. That extends to even not having enough counter space to hold coffee cups that customers have ordered ahead of time, much less including things like NFC readers or QR codes — the latter of which has proved wildly popular and effective throughout Asia thanks to services like Alipay and WeChat. And that’s largely a result of iOS and Android, the main platforms in North America, not really doing a lot with QR codes for a very long time. Reddy said that North America was making some progress, especially when it came to NFC, but for now the company still has to figure out unique ways to connect users to those restaurants.
That can take a lot of different forms. While Ritual has to figure out how to create a seamless experience that covers a lot of different restaurants or shops, Reddy said the startup still has to offer those same stores some kind of control over the experience. That means giving those customers some value proposition beyond just telling them to sign up for another order-ahead app. Ritual, for example, lets restaurants who onboard Ritual customers themselves keep the full transaction for a purchase, while it takes a small slice off other transactions. That, in addition to other marketing options, helps restaurants control their own destiny, he said.

Of course, at its heart, it’s an order-ahead app — even with that social experience on top of it. And if you’ve ever looked at where to eat nearby with coworkers, you’ve probably checked Yelp or a few other places, and possibly even settled the argument with a giant order on an online ordering platform like DoorDash or Seamless. All these have already tapped that user experience, and it’s not clear if Ritual would be able to clear enough room should any one of them go after a similar experience while already having that customer and user relationship, in addition to being the spot customers go already. In the end, Reddy says that it’ll come down to users having a few apps, and hopes that by offering restaurants flexibility and focusing on the hyper-local idea of just a single office building will help build up that moat.

“The way that things have played out in Asia [with platforms like WeChat] is exactly striking the right balance between a platform and giving stores control,” Reddy said. “When you think of the consumer view, people — for the same reason you don’t have 10 retail apps — don’t have 10 food apps. You’re not gonna download an app for every neighborhood spot. It’s not that these apps are bad or don’t work well, people are just not gonna download 10 apps. There’s gonna be a handful of platforms people are going to use to access their neighborhoods. We have to have a unified platform, but give restaurant partners enough control, not only over being able to speak with their customers, but control for the look and feel of their storefront. That’s the middle ground we’re looking to find, which we think is a win for customers and our storefronts.”


https://ift.tt/2Hp9tdO Order-ahead app Ritual picks up $70M to rethink the social office lunch break https://ift.tt/2kTY3pU

Europe to cap intra-EU call fees as part of overhaul to telecoms rules

{rss:content:encoded} Europe to cap intra-EU call fees as part of overhaul to telecoms rules https://ift.tt/2JkvPyY https://ift.tt/2xJJQ8g June 06, 2018 at 12:11PM

European Union institutions have reached a political agreement over an update to the bloc’s telecoms rules that’s rattled the cages of incumbent telcos.

Agreement was secured late yesterday after months of negotiations between the EU parliament and Council, with the former pushing for and securing a price cap on international calls within the bloc — of no more than 19 cents per minute. Texts will also be capped at a maximum of 6 cents each, Reuters reports.

While roaming charges for EU travelers were abolished across the bloc last summer, the parliament was concerned that charges for calls and texts between EU Member States is often disproportionately high — hence pushing for the cap, which was not in the original EC proposal.

The Commission proposed a new European Electronic Communications Code back in 2016, to modernize telecoms rules that had stood since 2009 — to take account of technology and market shifts, and align the rules with its wider Digital Single Market strategy.

The proposal broadly focused on pushing for consistency in spectrum policy and management; reducing regulatory fragmentation; ensuring a level playing field for market players and protections for consumers; and incentivizing investment in high-speed broadband networks.

And on the incentivization front, the new rules agreed yesterday update the powers of national regulators to act against dominant players — such as by being able to impose access to their network.

For a case study on why such interventions might be necessary you could look at the fiber investment and network-access foot-dragging of a former incumbent telco such as BT in the UK, for example, which has long favored eking out copper. While its network infrastructure division OpenReach was last year ordered to be legally separated — around a decade after it was functionally separated by the regulator. Yet complaints over BT’s lack of investment in broadband infrastructure and access for rivals to its networks have, nonetheless, persisted.

On the consumer front, the new EU telecoms Code also includes measures intended to make it easier to change service provider and keep the same phone number; measures around tariff transparency to make it easier for people to compare contractual offers, and the ability to terminate a contract without incurring additional costs; as well as additional protections around bundled services.

For operators there are deregulation measures for co-investments — intended to promote “risk sharing in the deployment of very high capacity networks”. And the Code sets wireless spectrum licenses at at least 20 years — also intended to give carriers the “predictability” they need to speed up 5G and fiber deployments.

Though this is shorter than operators had hoped, and the European Telecommunications Network Operators’ Association (ETNO) — whose membership is made up of incumbent telcos such as BT — has been quick to voice its displeasure, describing the code as a “missed opportunity“, and complaining that it adds extra complexity while also failing to incentivize investment.

“The Code will not ignite the much needed rush to invest in 5G and fibre networks and it will add complexity to an already burdensome system,” it writes. “The agreed law foresees only limited progress on spectrum policy, a complex and watered down compromise on incentivising fibre investment, uncertain triggers for imposing regulatory remedies and no fair playing field for digital services users and providers.”

Smaller, fiber-to-the-home broadband players are sounding much happier though…

ETNO also criticizes what it describes as “the unfortunate decision to regulate intra-EU calls” — arguing this is an unjustified, populist measure, and sniping that it creates legal uncertainty by setting what it couches as “a highly dangerous precedent for all other European industries”.

That’s not the view of the European Consumer Organization, BEUC, which describes the measure as “a good next step towards a real single market for consumers”.

“Consumers should no longer have to worry about excessive costs when calling another EU country from home. The end of roaming charges was a big first step, but it did not deal with the high costs of phone calls to another EU country when at home,” its director general, Monique Goyens, told us in a statement.

“Market concentration is bad for prices and consumer choice. A small group of players should not be able to take control of the market. Thanks to what has been agreed, national regulators can take measures to intervene and maintain a healthy level of competition,” she added.

“Telecom services regularly rank among the top most complained-about markets. This new law upgrades some important consumer protection measures. Telecom clients will for instance be able to end their contract early and choose a better deal.”

And of course the Commission is putting a positive spin on the outcome, two years on from its proposal to modernize the rules.

In a statement welcoming the end of the negotiations, Andrus Ansip, the VP in charge of the Digital Single Market, said: “This agreement is essential to meet Europeans’ growing connectivity needs and boost Europe’s competitiveness. We are laying the groundwork for the deployment of 5G across Europe.”

In another supporting statement, Mariya Gabriel, commissioner for digital economy and society, described the new rules as “bold and balanced” — saying they would provide “faster access to radio spectrum, better services and more protection for consumers, as well as greater investment in very high speed networks”.

While political accord on the new telecoms code has indeed been reached between the EU institutions, members of the EU parliament and Council still need to vote to adopt it — after which the bloc’s Member States will have two years to transpose it into their national laws.

Marley Spoon, the cook-at-home meal kit service, announces IPO

Marley Spoon, the meal kit subscription service that competes with the likes of Blue Apron and HelloFresh, has filed for an IPO in Australia. The Berlin-headquartered company is aiming to raise 70 million Australian Dollars (approximately $53m), and has chosen to list on the Australian Securities Exchange (ASX) in part because Australia is one of its strongest markets. It also operates in the U.S. and in four European countries, including Germany.

The IPO, which should complete in early July, will give Marley Spoon an indicative market capitalisation of ~200 million AUD (~$152m) on listing, priced at $1.42 per CDI. The majority of capital to be raised has already been placed with various public market institutional investors in Australia and a number of other eligible jurisdictions, while a minority will be made available to Australian resident investors via an allocation from their broker in a couple of week’s time, as per regulatory rules.

As with a number of other competing recipe kit services, the Marley Spoon proposition sees it deliver pre-portioned fresh ingredients for each recipe offered, so as to make it easier, more inspiring, and more cost-effective to cook at home. However, co-founder and CEO Fabian Siegel — who was previously co-CEO of online take-out marketplace Delivery Hero — has long argued that the weekly grocery shop, and to some extent restuarants, is the company’s direct competition.

To help with this, in the U.S. Marley Spoon has a partnership with Martha Stewart under the Martha & Marley Spoon brand. More recently, the company launched a cheaper, more mass-market offering called Dinnerly in a bid to make meal-kits less price sensitive and widen the product category’s appeal.

Siegel says the primary channel of customer acquisition is via customer referrals — for which no incentives are currently offered. In terms of paid marketing, Facebook trumps Google, since nobody really searches for recipe kits online and awareness that the product category exists at all is and remains the main challenge.

To that end, Marley Spoon claims 110,000 active customers across Australia, the U.S., Austria, Belgium, Germany, and the Netherlands (about a tenth the size of HelloFresh in the U.S.), and has forecast revenue of 93 million Euros this year.

Regards the decision to list on ASX, as of March this year, Australia represented 37 per cent of its revenue, which is slightly ahead of the U.S. and Europe. Siegel also tells me Marley Spoon is already break-even in Australia and is expected to be profitable in the country in the second half of the 2018 financial year, a pattern the company is aiming to replicate in other markets.

Asked why Marley Spoon has shunned further VC or private equity funding, Siegel, who was previously a Partner at Rocket Internet’s venture arm GFC, says he wants to be in it for the long term, and that an IPO — which sees 34 per cent of the company listed — means that the management team retains control. “You shouldn’t just blindly do what other people do, you have to understand what venture capital means for you,” he says, noting that VC was crucial to start the business and get it off the ground, but now he has decided it is “not the right thing for us”.

Specifically, since the channel switch from offline to online hasn’t yet really happened — which Siegel says it will eventually — he believes an IPO buys Marley Spoon enough time to grow the company at the same pace as the market for online grocery develops, rather than spending excessively on customer acquisition and other short term growth strategies.

“It’s a unique approach… We are still at day one now and we still have to prove to ourselves and the rest of the world that this in the end will have been the better strategy,” he says, candidly. But if it is, there’s a lot more of the $6.1 trillion global grocery market to eat into.


https://ift.tt/eA8V8J Marley Spoon, the cook-at-home meal kit service, announces IPO https://ift.tt/2JhHAKR

MoloFinance scores £3.7M seed funding to offer a fully digital mortgage

MoloFinance, a London-based fintech that is developing a “fully digital” mortgage solution, has closed £3.7 million in seed funding. The round is led by Ubon Partners, a Nordic fund specialised in financial services, and will be used to launch the company’s first product release later this summer.

Initially targeting ‘Buy to Let’ mortgages — i.e. people looking to buy property as an investment — while the company works through its regulatory approval process with the FCA, MoloFinance wants to offer an end-to-end mortgage process that is entirely digital and with the ability to give a near-instant decision.

The idea, says the startup, is to provide a frictionless experience for the customer whilst helping to eliminate any unnecessary costs related to the current process. Once FCA approved, MoloFinance plans to begin offering residential mortgages, too.

“The problem is simple: getting a mortgage today is a terrible experience, a painful process, based on obsolete practices, outdated in any other consumer experience,” MoloFinance co-founder Francesca Carlesi tells me. “Just try to compare the 4-6 weeks paper-based process of getting a mortgage with the instant set up of a current account online now available in most challenger banks”.

Carlesi says the status quo is entirely unnecessary as the technology needed to offer something a lot better is already here. Furthermore, customers are more than ready and future generations will expect instant, digital mortgages. “At Molo we are simply making it happen now,” she says.

This has seen the MoloFinance team design a fully digital mortgage journey, where most decisions are automated, most of the information needed is sourced digitally, and where a transparent “robo-advisor” substitutes puts the interest of customers first. “The net result is that we give people what they deserve for the most important financial decision of their life: speed, ease and lower costs,” argues Carlesi.

Similar offerings are already up and running in the U.S. and Australia, but in the U.K. the most disruptive forces, in the form of Habito and Trussle, have taken aim at mortgage brokerage. Carlesi concedes that these companies “have done a great first step” that was hugely overdue and that they can be considered MoloFinance’s closest peers but that the business model is “radically different”.

“We are not a broker, we don’t intend to disrupt the broker market. We are instead focusing on the overall lending process, from beginning to the end, with the goal to make the overall process quick, easy and more convenient and ultimately provide fully digital instant mortgages online. So in short we tried to solve the full problem that customers face today. As solving only one part of it in our view doesn’t solve the problem at all”.

On how MoloFinance plans to generate revenue, Carlesi says the startup will take a small share of the money made from the interest that a customer pays on their mortgage, leaving the majority for its funding partners. It won’t charge customers any unnecessary additional fees (e.g. broker fees, arrangement fees).


https://ift.tt/eA8V8J MoloFinance scores £3.7M seed funding to offer a fully digital mortgage https://ift.tt/2JvZIzL

Tuesday, June 5, 2018

Patreon acquires Kit to let creators bundle merch in subscriptions

If content creators want to sell pricier monthly content subscriptions, offering stickers, pins, signed photos, or t-shirts can convince fans to pay a higher fee and keep them loyal with a physical connection. That’s why patronage platform Patreon just acquired Kit, a startup building a merchandise logistics backend so creators don’t have to fiddle with spreadsheets and stuff envelopes themselves.

“Over 60 percent of today of Patreon creators either want to or are already delivering some kind of physical merchandise” says Patreon’s VP of Product, Wyatt Jenkins. Together, they could help Patreon creators develop merch items that fans subscribe to get ahold of, potentially shelling out for $10 or $20 per month tiers rather than basic $1 or $5 online content-only tiers.

The deal could also help Patreon stay ahead of YouTube and Facebook, which are encroaching on its subscription patronage model. Patreon now has 2 million patrons backing 100,000 creators. It paid out $350 million over its first 5 years through 2017, and expects to send creators another $300 million in 2018, while taking a 5 percent cut.

Financial terms of the deal were not disclosed. 90 percent of Kit team, mostly product and engineering talent, will join San Francisco-based Patreon though they’ll stay put in NYC as a satellite office the rest of the year. Kit had raised $2.5 million from Social Capital, Expa, #Angels, Precursor, and Stanford’s StartX, as well as angels like Ellen Pao and Slack’s April Underwood.

“When we think about merch, it’s never been fully about the thing — the sticker or the t-shirt — there’s this relationship. This human-to-human connection” says Kit co-founder and CEO Camille Hearst.

Kit was in the process of pivoting towards merchandise logistics and raising a Series A when it began talks with Patreon, leading to the acquisition. The startup was originally built as a way for social media stars and online celebrities to earn affilliate marketing fees by recommending products to fans through Kit, which took a cut of the referral dollars. Some creators showing off their “Kit” of camera equipment, sportswear, or caffeination supplies were earning tens of thousands of dollars.

“We were at a stage where everything was going in the right direction. We had seen strong growth in monthly active users and how much creators were making” Hearst says, noting Kit had reached $15 million in gross merchandise value. “It just seemed like we would be able to accelerate what we were doing by joining with Patreon. Merch is very transaction focused compared with a subscription.” Hearst explains, touting the high lifetime value of recurring payments over one-off purchases. “You can help creators earn a lot more money if you use merch to sell subscriptions.”

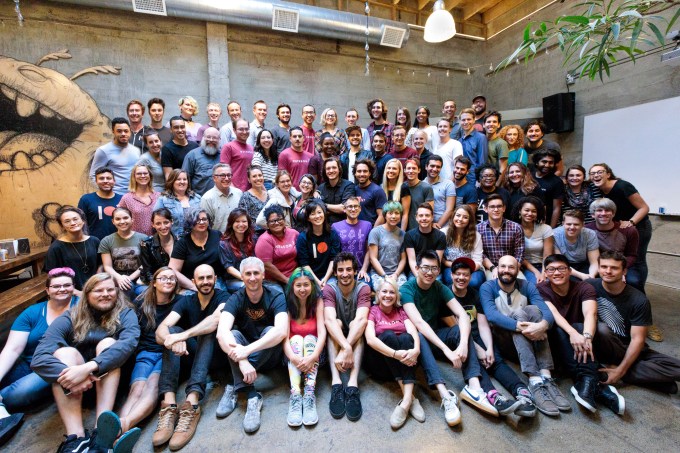
The pre-Kit Patreon team

The plan at Patreon is to build out a new open merchandise provider platform. Creators will be able to choose between a variety of merch partners ranging from those that turn their existing logo into physical goods to those that will design items based on merely vague ideas from the star. But in the meantime, Kit won’t be shutting down or ditching its affilliate program because “we don’t want to turn off any revenue streams” that creators depend on, Hearst promises.

“Right now creators have to choose between different merch partners” without collective bargaining power or enoug data to know what works, says Jenkins. “We can have set pricing for all those merch partners that will be lower than they can get on their own”, while alleviating creators from having to juggle spreadsheets of who gets what and mailing it all themselves.

The plan for Patreon to monetize merch is a little less clear, though Jenkins says “We’re going to grow the pie and we want a piece of the growth.” The idea is that using Patreon’s merchandise platform will incur extra fees beyond the skimpy 5 percent it earns on subscriptions. If adding a merch item significantly boosts the subscriber number for a certain tier, Patreon will take a TBD cut.

“We want creators to make a living. That’s not a side hustle. You have to make more money year over year, You have to be able to do things like buy a house or get healthcare” Jenkins concludes. “All the other platforms are ‘give us your content and we’ll give you a little side change’. That kind of led us down the mech path. Creators are were begging for merch.”


from Social – TechCrunch https://ift.tt/2xLeKgf Patreon acquires Kit to let creators bundle merch in subscriptions Josh Constine https://ift.tt/2JgqzAr
via IFTTT

Patreon acquires Kit to let creators bundle merch in subscriptions

If content creators want to sell pricier monthly content subscriptions, offering stickers, pins, signed photos, or t-shirts can convince fans to pay a higher fee and keep them loyal with a physical connection. That’s why patronage platform Patreon just acquired Kit, a startup building a merchandise logistics backend so creators don’t have to fiddle with spreadsheets and stuff envelopes themselves.

“Over 60 percent of today of Patreon creators either want to or are already delivering some kind of physical merchandise” says Patreon’s VP of Product, Wyatt Jenkins. Together, they could help Patreon creators develop merch items that fans subscribe to get ahold of, potentially shelling out for $10 or $20 per month tiers rather than basic $1 or $5 online content-only tiers.

The deal could also help Patreon stay ahead of YouTube and Facebook, which are encroaching on its subscription patronage model. Patreon now has 2 million patrons backing 100,000 creators. It paid out $350 million over its first 5 years through 2017, and expects to send creators another $300 million in 2018, while taking a 5 percent cut.

Financial terms of the deal were not disclosed. 90 percent of Kit team, mostly product and engineering talent, will join San Francisco-based Patreon though they’ll stay put in NYC as a satellite office the rest of the year. Kit had raised $2.5 million from Social Capital, Expa, #Angels, Precursor, and Stanford’s StartX, as well as angels like Ellen Pao and Slack’s April Underwood.

“When we think about merch, it’s never been fully about the thing — the sticker or the t-shirt — there’s this relationship. This human-to-human connection” says Kit co-founder and CEO Camille Hearst.

Kit was in the process of pivoting towards merchandise logistics and raising a Series A when it began talks with Patreon, leading to the acquisition. The startup was originally built as a way for social media stars and online celebrities to earn affilliate marketing fees by recommending products to fans through Kit, which took a cut of the referral dollars. Some creators showing off their “Kit” of camera equipment, sportswear, or caffeination supplies were earning tens of thousands of dollars.

“We were at a stage where everything was going in the right direction. We had seen strong growth in monthly active users and how much creators were making” Hearst says, noting Kit had reached $15 million in gross merchandise value. “It just seemed like we would be able to accelerate what we were doing by joining with Patreon. Merch is very transaction focused compared with a subscription.” Hearst explains, touting the high lifetime value of recurring payments over one-off purchases. “You can help creators earn a lot more money if you use merch to sell subscriptions.”

The pre-Kit Patreon team

The plan at Patreon is to build out a new open merchandise provider platform. Creators will be able to choose between a variety of merch partners ranging from those that turn their existing logo into physical goods to those that will design items based on merely vague ideas from the star. But in the meantime, Kit won’t be shutting down or ditching its affilliate program because “we don’t want to turn off any revenue streams” that creators depend on, Hearst promises.

“Right now creators have to choose between different merch partners” without collective bargaining power or enoug data to know what works, says Jenkins. “We can have set pricing for all those merch partners that will be lower than they can get on their own”, while alleviating creators from having to juggle spreadsheets of who gets what and mailing it all themselves.

The plan for Patreon to monetize merch is a little less clear, though Jenkins says “We’re going to grow the pie and we want a piece of the growth.” The idea is that using Patreon’s merchandise platform will incur extra fees beyond the skimpy 5 percent it earns on subscriptions. If adding a merch item significantly boosts the subscriber number for a certain tier, Patreon will take a TBD cut.

“We want creators to make a living. That’s not a side hustle. You have to make more money year over year, You have to be able to do things like buy a house or get healthcare” Jenkins concludes. “All the other platforms are ‘give us your content and we’ll give you a little side change’. That kind of led us down the mech path. Creators are were begging for merch.”


https://ift.tt/2xLeKgf Patreon acquires Kit to let creators bundle merch in subscriptions https://ift.tt/2JgqzAr

Coya raises $30 million to launch its insurance service in Europe

Coya, a Berlin-based insurance startup, has raised $30 million in new cash as investors around the world continue to see opportunities in modernizing the insurance industry.

Founded by two early employees at the European credit and risk assessment unicorn startup Kreditech (which raised €110 million from the Naspers subsidiary PayU) and two seasoned executives from the European insurance industry, Coya is coming to market in Germany with a new renter’s insurance service.

For Coya’s co-founder Andrew Shaw, the new company was an opportunity to apply his experience creating credit and risk assessment products to an industry whose cumbersome inability to use technology had affected him personally.

The idea for Coya hit Shaw when he was traveling on the Gili Islands off the coast of Indonesia. It was there, while Shaw was trying to get information on his insurance as he recovered from an illness, that he decided to start his technologically enabled insurance business.

“I knew I had one or two [policies] somewhere, but couldn’t find them in email or log into the webpage, I felt left alone and realized how insurers are not concentrating on their product experience,” Shaw wrote to me in an email. “A bad insurance experience, plus the opportunity to create awesome technology in an outdated financial space was a challenge I couldn’t ignore.”

In 2016, Kreditech’s first employee launched the company with co-founders Sebastian Villaroel, a fellow former Kreditech employee; Peter Hagen, the former chief executive of Vienna Insurance Group; and Thomas Münkel, a longtime executive at Allianz and the former chief operating officer of Uniqa Insurance.

Peter Hagen, Andrew Shaw, Sebastian Villaroel and Thomas Münkel, co-founders Coya AG Berlin/Courtesy: Christian Manthey Photography

The company has raised a total of $40 million for its service from investors, including Valar Ventures (the Peter Thiel-backed investment firm), eVentures, La Famiglia and a slew of angel investors.

With the money, Coya hopes to establish its footprint in its first market — Germany — before expanding to the rest of Europe. Powering that expansion is a German insurance license, which the company is close to receiving, according to Shaw. Once that license is acquired, the company can access all 550 million European Union residents under the watchful eye of Germany’s regulators.

Although, Coya is starting with renter’s insurance, Shaw and his co-founders have big plans for the company’s platform, with insurance products across property, accident, personal liability and personal finance.

The company has 55 people on staff now, and expects to increase its headcount as a result of the new financing, according to Shaw.

Shaw says that Coya is different from many of the other startups pitching insurance products across Europe thanks to its push to receive regulatory approval and issue its own policies. That’s also created more capital requirements for the business starting out.

There’ve been a slew of insurance startups coming to market with novel twists on the service. Among them, Shaw pointed to Lemonade in the U.S., wefox in the Germany and the U.K.-based Sherpa as companies bringing innovation to the old industry.


https://ift.tt/2JbRMEj Coya raises $30 million to launch its insurance service in Europe https://ift.tt/2xPJug2

Highfive’s video conferencing platform is now available through Ingram Micro and at Best Buy

Highfive, a Redwood City-based startup, offers businesses an integrated video conferencing service through its own custom meeting room hardware. While Highfive has been quite successful in selling its service and hardware online, the company today announced that it is adding Best Buy and Ingram Micro as distribution partners in an effort to expand its reach to a wider audience.

Today’s announcement follows the company’s $32 million Series C round in February. That round was led by Dimension Data, a global technology integrator owned by Japan’s NTT Group. As part of this deal, Highfive signed a distribution deal with Dimension Data and it’s clear that company’s focus right now is on getting more of these deals on the books.

In the enterprise world that Highfive is targeting, getting distribution from Ingram Micro is obviously a big deal. The company has 155 distribution centers and works with over 200,000 resellers. And it’s through Ingram Micro that Best Buy for Business will also now offer Highfive’s products.

Since Highfive typically makes access to its services and hardware available through a subscription, this will be a slightly different sales process than usual, but to support its resellers, Highfive is launching an official channel program to help dealers sell its products effectively.

Pricing remains the same, though, no matter whether you go through Highfive’s online store or a reseller. Software-only plans start at $9.99 per month and user (which is paid annually) and then you can add the hardware on top of that for $99 per month (also paid annually) without any upfront cost.

“As the business demand for a conferencing platform that can manage every use case grows, our channel partner initiatives are paramount to equipping enterprises with the solution they need to improve team communication and workflow,” said Bobby Marhamat, CRO of Highfive. “Our certified partners are more than just a resource to deliver Highfive, we want to empower them with everything they need to provide customers full service—from purchase to deployment to maintenance.”


https://ift.tt/eA8V8J Highfive’s video conferencing platform is now available through Ingram Micro and at Best Buy https://ift.tt/2LZsQOd

TransferWise’s next partnership could be with U.K. challenger bank Monzo

Hot on the heels of announcing that it has partnered with France’s BPCE Groupe, TransferWise could be about to unveil another partnership with a bank. According to sources, the international money transfer service and European unicorn is working the fast-growing with U.K. challenger bank Monzo.

The tie-in will likely see TransferWise functionality offered within Monzo’s mobile banking app, courtesy of the TransferWise API. It will give Monzo customers the ability to send money in various supported currencies at the ‘mid market’ rate in addition to TransferWise’s low and transparent fees.

Along with the newly-announced partnership with BPCE Groupe — which won’t ship until next year — TransferWise is also working with Estonia’s LHV, and German challenger bank N26 (which also has plans to launch in the U.K.).

A partnership with U.K. challenger bank Starling was also announced last year, but integration with the bank’s app never materialised and TechCrunch learned last week that the partnership has now dissolved entirely. That is particularly noteworthy given that Monzo and Starling are direct competitors with an interesting shared history, shall we say.

Meanwhile, if confirmed, we can probably chalk this up as a decent win for TransferWise, which is best known for its consumer-facing international money transfer app, but has always had ambitions of being a broader platform play.

In fact, the company is attempting to position itself as entirely agnostic on how customers access the service: the more money moving via its infrastructure, the better, whilst economies of scale also mean potentially lower fees on specific routes. This can be done directly via the TransferWise app and service for both consumers and SMEs, via third-party integrations, such as with incumbent and challenger banks, or via the company’s own Borderless account. In all three cases, TransferWise generates revenue, regardless.

I’ve reached out to both TransferWise and Monzo for comment and will update this post if and when I hear back.


https://ift.tt/eA8V8J TransferWise’s next partnership could be with U.K. challenger bank Monzo https://ift.tt/2sHK8qt

Scooter startup Lime is reportedly raising $250M led by Uber investor GV

{rss:content:encoded} Scooter startup Lime is reportedly raising $250M led by Uber investor GV https://ift.tt/2LnrMCx https://ift.tt/2J8YU4m June 05, 2018 at 05:04PM

It’s scooters all the way down this morning, with Lime also reportedly raising $250 million in a funding this morning after a new Delaware filing this morning indicated that competitor Bird authorized the sale of up to $200 million in shares.

GV (formerly Google Ventures) is leading this round, according to the report by Axios, as the massive land grab for a stake in the scooter wars continues to heat up — whether that’s funding or actual scooters piling up on the sidewalk. Both companies have faced pushback from some city regulators (probably on the basis of tripping over them and falling on your face), but it still means the venture community is still salivating over potentially the next major mode of metropolitan transportation. Most venture investors in the Valley argue scooters make sense for short trips throughout areas that are just too far to be considered a trek, but too close that it would be a waste of time and money to call a ride share like Uber or Lyft.

Given that Uber exposed a massive hole for easier transportation in major metropolitan areas — and potentially replacing cars in those areas — getting into the next big transportation revolution is more than tempting enough for firms like GV (which is also an investor in Uber). Lime was previously reported to be seeking up to $500 million in funding and was taking meetings with some major firms in Silicon Valley over the past few weeks. It might not get that, but a $250 million influx might be plenty to try to continue to ramp up its business and get more rides on board. Axios is reporting that Lime has told investors users have taken 4.2 million rides and each scooter gets 8 to 12 rides per day.

Still, while it’s not $500 million, there’s plenty of interest in the on-demand scooter business — challenges of keeping them charged and intact included — that Bird has authorized the sale of up to $200 million in new shares at a $1 billion valuation just months after its previous round. So it might not be surprising if this, too, ends up as kind of a rolling process where Lime eventually gets all the capital it sought.

Scooter startup Bird has authorized sale of $200M in shares in latest funding round

{rss:content:encoded} Scooter startup Bird has authorized sale of $200M in shares in latest funding round https://ift.tt/2svYScK https://ift.tt/2xH79Q4 June 05, 2018 at 04:08PM

Bird, the scooter startup whose scooters you might have seen fallen over on the sidewalk in a major metro area, has authorized a new $200 million round of funding that could value the startup at around $1 billion post-money, according to a certificate of incorporation filed in Delaware.

The latest Bird round has been pretty widely reported, suggesting that the company is raising $150 million at a $1 billion valuation. That, too, comes amid a big effort by competitor Lime to raise a big funding round. These documents indicate that the company has authorized the sale of those shares, though it may not fully fill out the round. The certificate of incorporation document was provided be Lagniappe Labs, creator of the Prime Unicorn Index.

The document indicates that Bird has authorized the sale of 31.5 million new shares in its financing round at a value of $6.15 per share, which if fully sold could net the startup as much as $200 million in this round. This round would value the company at just over $1 billion, a new financing round that follows up a $100 million round announced in March.

These kinds of rolling rounds are not completely uncommon. Instead of bundling everything together in a single round, startups may sometimes have a process that includes follow-on investment rounds, of which this may be a component. The last funding round in March valued the company at around $300 million.

Needless to say, scooters are a hot market right now even if they are facing a lot of friction when it comes to dealing with leaving their scooters everywhere around cities. But running startups that are hardware-focused — especially on-demand ones that have to manage a network of scooters that need to have enough of a charge to get someone from point A to point be, lest they have a bad experience and switch to an alternative, can be an expensive proposition. The hardware component itself, too, can be a tough business.

Scooter startup Lime is reportedly raising $250M led by Uber investor GV

It’s scooters all the way down this morning, with Lime also reportedly raising $250 million in a funding this morning after a new Delaware filing this morning indicated that competitor Bird authorized the sale of up to $200 million in shares.

GV (formerly Google Ventures) is leading this round, according to the report by Axios, as the massive land grab for a stake in the scooter wars continues to heat up — whether that’s funding or actual scooters piling up on the sidewalk. Both companies have faced pushback from some city regulators (probably on the basis of tripping over them and falling on your face), but it still means the venture community is still salivating over potentially the next major mode of metropolitan transportation. Most venture investors in the Valley argue scooters make sense for short trips throughout areas that are just too far to be considered a trek, but too close that it would be a waste of time and money to call a ride share like Uber or Lyft.

Given that Uber exposed a massive hole for easier transportation in major metropolitan areas — and potentially replacing cars in those areas — getting into the next big transportation revolution is more than tempting enough for firms like GV (which is also an investor in Uber). Lime was previously reported to be seeking up to $500 million in funding and was taking meetings with some major firms in Silicon Valley over the past few weeks. It might not get that, but a $250 million influx might be plenty to try to continue to ramp up its business and get more rides on board. Axios is reporting that Lime has told investors users have taken 4.2 million rides and each scooter gets 8 to 12 rides per day.

Still, while it’s not $500 million, there’s plenty of interest in the on-demand scooter business — challenges of keeping them charged and intact included — that Bird has authorized the sale of up to $200 million in new shares at a $1 billion valuation just months after its previous round. So it might not be surprising if this, too, ends up as kind of a rolling process where Lime eventually gets all the capital it sought.


https://ift.tt/eA8V8J Scooter startup Lime is reportedly raising $250M led by Uber investor GV https://ift.tt/2LnrMCx

blogger better Headline Animator