l
l
blogger better. Powered by Blogger.

Search

Labels

blogger better

Followers

Blog Archive

Total Pageviews

Labels

Download

Blogroll

Featured 1

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 2

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 3

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 4

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 5

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Tuesday, January 5, 2021

Kyte raises $9 million to deliver rental cars to your doorstep

More than two years ago, Ludwig Schoenack, Nikolaus Volk and Francesco Wiedemann looked at the bevy of scooter services, ride-hailing apps, public transit and car-sharing options available in most urban centers in the United States and saw a gap in the mobility market.

Consumers who didn’t want to own a car, but needed one for a few days or weeks had two options: head to a car rental center, likely located at an airport or outside the city center, or turn to a car-sharing platform. The three friends — all German immigrants whose paths had crossed in San Francisco — decided to pool their collective expertise from BMW, McKinsey and Uber and launch Kyte to create a new kind of car rental experience without taking on the costly business of owning and maintaining large fleets.

Kyte built a fleet-logistics platform that lets consumers rent vehicles through their app or website. The vehicles, which are located in hubs throughout a city center, are delivered by gig economy workers right to the renters’ home. Kyte also handles the pickup and refuels the vehicle for no extra charge.

“We still believe people own cars because they want it outside their door, so we thought why don’t we put it right there,” Schoenack said in a recent interview.

Kyte partners with car rental firms and other companies that manage fleets, allowing the startup to focus on consumers and the tech.

The startup, which launched in late 2018 and operates in Boston, Los Angeles and San Francisco, has caught the attention of capital of investors. The startup said Tuesday it has raised $9 million in funding from DN Capital and Amplo VC. Numerous individual investors from the mobility industry also participated, including former Uber executives Ed Baker, Jörg Heilig, Josh Mohrer and William Barnes, as well as Lime co-founder Toby Sun and Kayak and Travelocity co-founder Terry Jones.

The funds are already being put to work to help drive Kyte’s expansion into markets, starting with Washington, D.C.
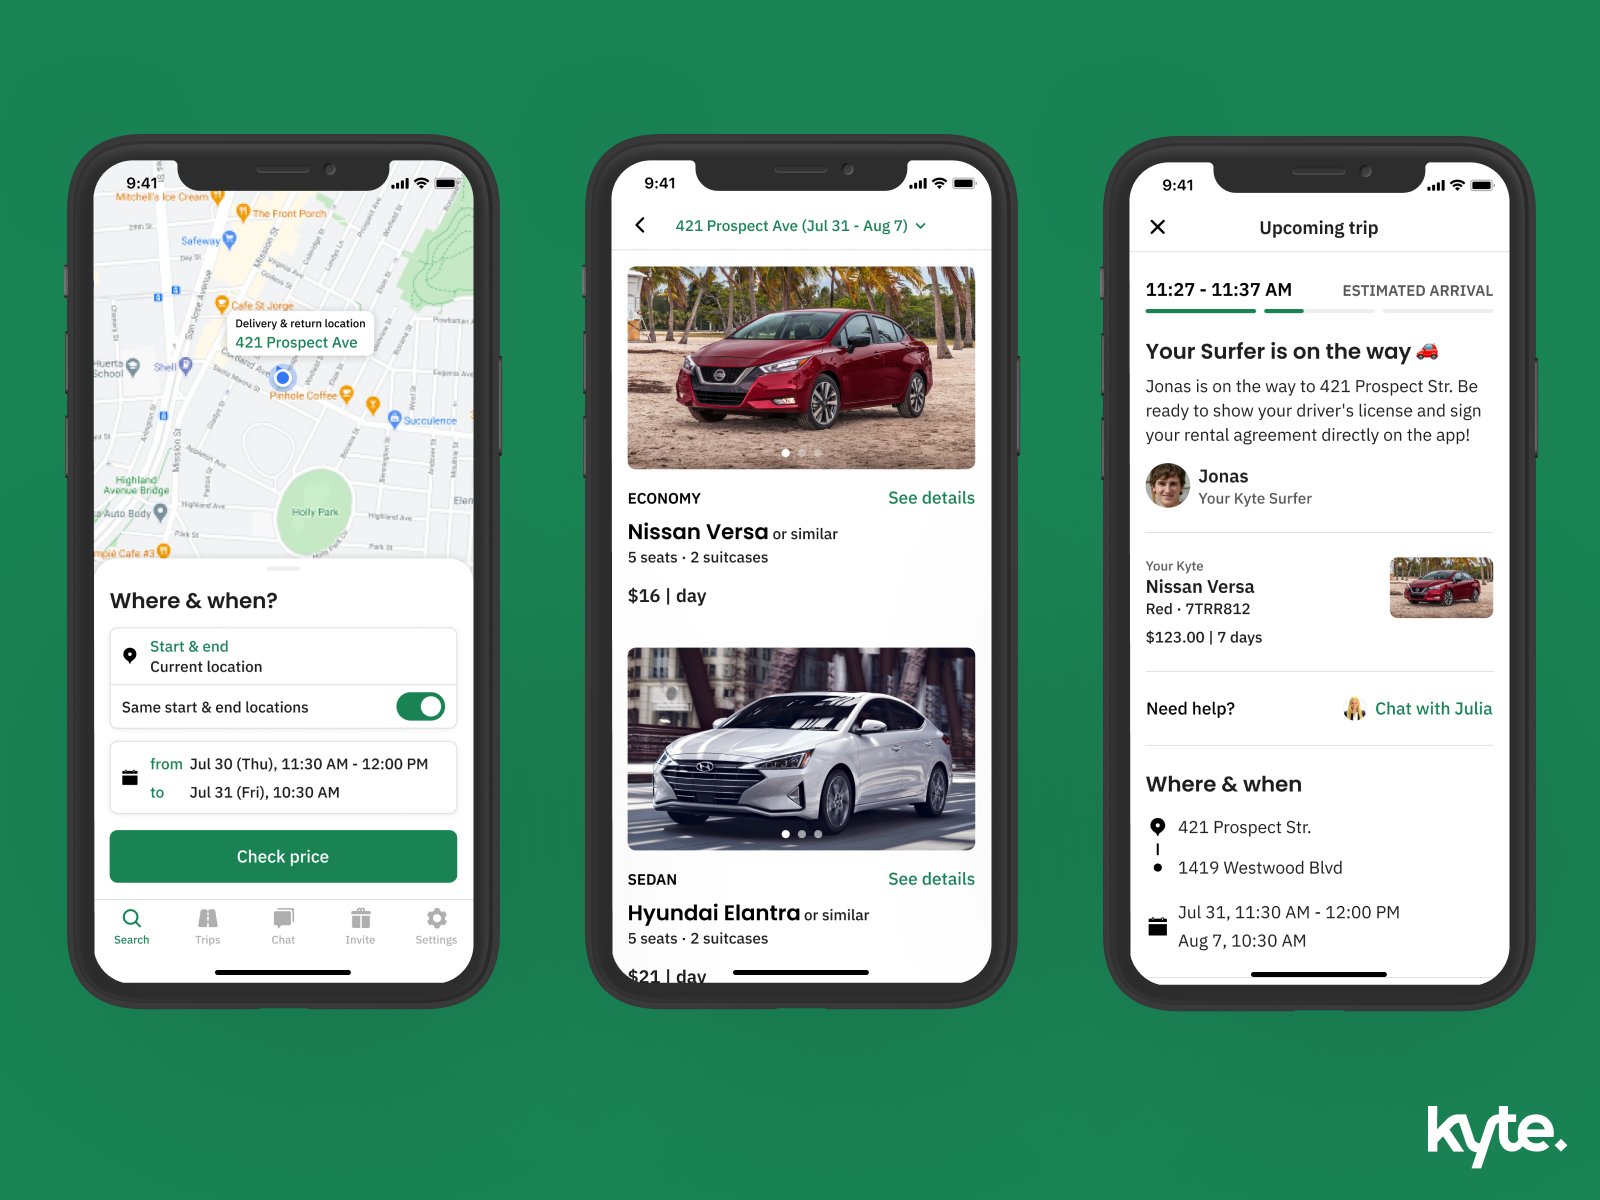
Kyte car rental app

Image Credits: Kyte

Kyte’s founders wouldn’t disclose their revenue, except to say it’s generating a “solid six-figure” amount of revenue monthly. Schoenack added that Kyte’s monthly revenue has grown 400% since March as more consumers have turned to cars during the COVID-19 pandemic.

“Even before COVID was on the horizon, it was clear that we needed to change the way we interact with cars,” Schoenack said. Consumers have been more willing to try alternatives like Kyte to travel as COVID-19 has turned many off from air travel.

Despite this fast growth, Schoenack said more than half of Kyte’s bookings come from recurring users.

Kyte has also found its clients — which Schoenack would only describe as the biggest rental car companies in the country — are willing and enthusiastic participants since it helps get vehicles in the hands of customers. Rental car companies were hit hard by COVID-19 since the bulk of operations are at airports. These companies were left with millions of dollars of depreciating assets that weren’t generating any revenue.

DN Capital’s co-founder and managing director Steve Schlenker believes that Kyte will be a core building block to the future of mobility.

“The pandemic has accelerated the transformation of cities and consumer behavior with respect to transportation,” Schlenker said. “Kyte’s unique operations layer facilitates this transformation while providing a level of service and convenience that other solutions fail to meet.”


https://ift.tt/2MBjgG9 Kyte raises $9 million to deliver rental cars to your doorstep https://ift.tt/35cbgBH

Divvy raises $165M as the spend management space stays red-hot

Today Divvy, a Utah-based startup that focuses on corporate spend management, announced that it has closed a $165 million round at a $1.6 billion valuation. The company said that the new capital was raised from Hanaco, Schonfeld, PayPal Ventures and Whale Rock, along with a cadre of prior investors.

The new investment is not Divvy’s first megaround of private capital. The well-known startup raised $200 million in April of 2019. TechCrunch reported at the time that that round valued Divvy at around $700 million, making today’s deal a more than 2x increase in valuation for the company.

Divvy exists amongst the current generation of Utah-based tech upstarts that are keeping the state’s tech scene in the broader startup conversation. Podium fits in the same cohort, for example, while Qualtrics feels like it’s from the preceding peer group.

Divvy’s market, the corporate spend management space — broadly, corporate cards and software that helps firms manage and limit expenses — is incredibly active today as businesses look to modernize their financial infrastructure. The new capital for Divvy comes after multiple other competitors recently announced fresh funds itself, for example. Let’s take a look at who Divvy is taking on with its new round.

Competition

A few weeks back Ramp, another corporate-cards-and-software startup, announced a $30 million raise and that it had reached $100 million in spend through its service in its first 18 months of business. At the same time Divvy shared with TechCrunch that it had seen 120% customer growth and over 100% growth in platform spend in 2020, compared to 2019. At the time, Brex, which also competes in the corporate spend space, declined to share metrics.

That Divvy was able to raise so much capital given its recent growth rates is not surprising. But that so many companies in its sector are managing similarly strong-to-line expansion stands out. After covering the Ramp round in December and noting Divvy’s metrics at the same time, both Airbase (more here) and Teampay (more here) reached out with numbers of their own.

Teampay reiterated its October-era metrics: that it has seen its annual recurring revenue (ARR) grow by 320% and its total spend grow by 800% since its then year-ago Series A. Airbase noted what it described as 250% growth in ARR — up by 2.5x, in other words — and 700% growth in payment volume (annualized).

Divvy, Teampay and Airbase are therefore growing like all heck, though in slightly different fashions. Divvy and Ramp offer their corporate spend products and software for free, taking a slice of payment volume through interchange revenues. Teampay and Airbase generate incomes from interchange as well, but also charge for their software. This gives them both spend and software revenues.

Which brings us back to Divvy’s news from today. I normally avoid quoting from releases, but in today’s case a paragraph is worth sharing:

The valuation of $1.6 billion and the addition of key investors validates Divvy’s ambition to modernize financial processes by combining credit, vendor, and spend management into a single platform. With this round of funding, Divvy plans to invest heavily in product development and engineering in order to accelerate their future roadmap.

Divvy is going to invest heavily in product? That makes sense. But to give away its software forever just seems odd. Some of its competitors are charging for theirs! Why not Divvy as well?

We’ll see, but what is clear today is that the capital that has gone into startups in Divvy’s cohort was put into a niche that has shown huge demand. So, expect to hear more from this product area in 2021.


https://ift.tt/eA8V8J Divvy raises $165M as the spend management space stays red-hot https://ift.tt/38gyt80

Chronosphere nabs $43M Series B to expand cloud native monitoring tool

Chronosphere, the scalable cloud native monitoring tool launched in 2019 by two former Uber engineers, announced a $43.4 million Series B today. The company also announced that their service was generally available starting today.

Greylock, Lux Capital and venture capitalist Lee Fixel, all of whom participated in the startup’s $11 million Series A in 2019, led the round with participation from new investor General Atlantic. The company has raised $54.4 million.

The two founders, CEO Martin Mao and CTO Rob Skillington, created the open-source M3 monitoring project while they were working at Uber, and left in 2019 to launch Chronosphere, a startup based on that project. As Mao told me at the time of the A round, the company wanted to simplify the management of running the open source project:

M3 itself is a fairly complex piece of technology to run. It is solving a fairly complex problem at large scale, and running it actually requires a decent amount of investment to run at large scale, so the first thing we’re doing is taking care of that management,

He said that the company spent most of last year iterating the product and working with beta customers, adding that they certainly benefited from building the commercial service on top of the open-source project.

“I think we’re lucky that we have the foundation already from the open-source project, but we really wanted to focus a lot on building a product on top of that technology and really have this product be differentiated, so that was most of the focus of 2020 for us,” he said.

Mao points out that he and Skillington weren’t looking for this new round of funding as they still had money left from the A round, but the company’s previous investors approached them and they decided to strike to add additional money to the balance sheet, which would help grow the company, attract employees and help reassure customers they had plenty of capital to continue building the product and the company.

As the company has developed over the last year, it has been adding employees at a rapid clip, growing from 13 at the time of the A round in 2019 to 50 today with plans to double that by the end of next year. Mao says the founders have been thinking about how to build a diverse company from its early days.

“So [ … ] beginning last year we were making sure we were hiring the right leaders, and the right recruiting team who also care about diversity, then following that we made company-wide goals and targets for both gender and ethnic diversity, and then [we have been] holding ourselves accountable on these particular goals and tracking against them,” Mao said.

The company has been spread out from the beginning, even before COVID, with offices in Seattle, New York and Lithuania, and that has helped in terms of having a broader base to recruit from. Mao wants to remain mostly remote whenever it’s possible to return to the office, but maintain hubs on each coast where employees can meet and see each other in person.

With the product generally available today, the company will look to expand its customer base, and with the open-source project to drive interest, they have a proven way to attract new customers to the commercial product.


https://ift.tt/eA8V8J Chronosphere nabs $43M Series B to expand cloud native monitoring tool https://ift.tt/2KVnlog

What’s going on with fintech venture capital investment?

Over the next few weeks, the venture capital industry will compile and release data concerning its Q4 2020 performance, capping a year that saw the world of private capital freeze, thaw and burn.

But we can get a peek at a critical part of the VC universe early, thanks to a preview of global fintech investment results from CB Insights. The dataset deals with worldwide investments into fintech companies from the start of October through December 12.


The Exchange explores startups, markets and money. Read it every morning on Extra Crunch, or get The Exchange newsletter every Saturday.


Given that the last two weeks of the year are not famous for productivity, the dataset we have should prove representative for this critical slice of the venture capital market. (For our look at the third-quarter fintech VC market, head here.)

To be honest, I didn’t plan on writing up this data when I first dug into it; I was prepping for later releases, hoping to ground myself ahead of the full numbers. However, the collected results aligned with several themes that cropped up during 2020, making it a representative capstone of sorts concerning the year’s venture capital market. So it was too interesting to not unpack.

What happened to fintech venture capital investment in Q4 and 2020? Some startup stages and regions did well, but amidst the good news, one of the hotter domestic segments of startup land is not set to have a good global year. Let’s get into the numbers.

A final warning: Although these results are missing a few weeks’ worth of inputs, we believe these numbers will prove more than directionally accurate when all results are tallied and released by the various organs of venture data tracking.

North America and Europe shine, Asia falls

Using numbers that include projections for the rest of 2020, it’s clear that the fintech venture capital world is not equally distributed. If you are reading this in the United States, for example, or the U.K., you might be surprised to learn that CB Insights expects global fintech venture capital deal and dollar volume to fall in 2020. Surely not, with all the neobank and trading-platform deals we saw?

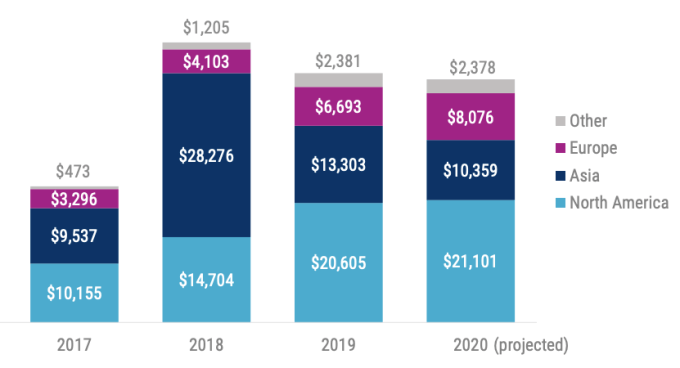
Yes, actually, because while fintech investment has risen in dollar terms in both North America and Europe, huge declines in Asia have overshadowed results in the other two regions. Here’s the clip of the preview chart:

Image Credits: CB Insights


https://ift.tt/3bb8osQ What’s going on with fintech venture capital investment? https://ift.tt/3onuzzS

What’s going on with fintech venture capital investment?

Over the next few weeks, the venture capital industry will compile and release data concerning its Q4 2020 performance, capping a year that saw the world of private capital freeze, thaw and burn.

But we can get a peek at a critical part of the VC universe early, thanks to a preview of global fintech investment results from CB Insights. The dataset deals with worldwide investments into fintech companies from the start of October through December 12th.


The Exchange explores startups, markets and money. Read it every morning on Extra Crunch, or get The Exchange newsletter every Saturday.


Given that the last two weeks of the year are not famous for productivity, the dataset we have should prove representative for this critical slice of the venture capital market. (For our look at the third-quarter fintech VC market, head here.)

To be honest, I didn’t plan on writing up this data when I first dug into it; I was prepping for later releases, hoping to ground myself ahead of the full numbers. However, the collected results aligned with several themes that cropped up during 2020, making it a representative capstone of sorts concerning the year’s venture capital market. So it was too interesting to not unpack.

What happened to fintech venture capital investment in Q4 and 2020? Some startup stages and regions did well, but amidst the good news, one of the hotter domestic segments of startup land is not set to have a good global year. Let’s get into the numbers.

A final warning: although these results are missing a few weeks’ worth of inputs, we believe these numbers will prove more than directionally accurate when all results are tallied and released by the various organs of venture data tracking.

North America and Europe shine, Asia falls

Using numbers that include projections for the rest of 2020, it’s clear that the fintech venture capital world is not equally distributed. If you are reading this in the United States, for example, or the UK, you might be surprised to learn that CB Insights expects global fintech venture capital deal and dollar volume to fall in 2020. Surely not, with all the neobank and trading-platform deals we saw?

Yes, actually, because while fintech investment has risen in dollar terms in both North America and Europe, huge declines in Asia have overshadowed results in the other two regions. Here’s the clip of the preview chart:

Via CB Insights


https://ift.tt/3bb8osQ What’s going on with fintech venture capital investment? https://ift.tt/3onuzzS

TrendForce expects the smartphone market to slowly recover in 2021, but Huawei won’t benefit

{rss:content:encoded} TrendForce expects the smartphone market to slowly recover in 2021, but Huawei won’t benefit https://ift.tt/2Ljnodl https://ift.tt/3pUKZzI January 05, 2021 at 07:08AM

After a dismal year, the global smartphone market will slowly start recovering in 2021, predicts TrendForce. But Huawei won’t benefit and, in fact, will fall out of the research firm’s list of the world’s top six smartphone makers by production volume.

In 2020, global smartphone production dropped 11% year-over-year to 1.25 billion units. This year, TrendForce expects it to increase by 9% to 1.36 million units, as people replace old devices and demand grows in emerging markets. But even that slight recovery is contingent on how the pandemic continues to impact the economy and the global chip shortage that is currently causing production delays across almost the entire electronics industry.

In 2020, the top six smartphone brands in order of production volume were Samsung, Apple, Huawei, Xiaomi, OPPO and Vivo. But this year TrendForce expects Huawei to slip out of that ranking, with the new top-six list comprising Samsung, Apple, Xiaomi, OPPO, Vivo and Transsion.

Those six companies are expected to account for 80% of the global smartphone market in 2021, while Huawei will come in at seventh place.

The main reason for Huawei’s drop is the divestment of its budget smartphone brand, Honor. Huawei confirmed in November that it is selling Honor to a consortium of companies to save the division’s supply chain from the impact of United States government trade restrictions.

The spin-out was meant to shield Honor from the sanctions that have hurt Huawei’s business. But “it remains to be seen whether the ‘new’ Honor can capture consumers’ attention without the support from Huawei. Also, Huawei and the new Honor will be directly competing against each other in the future, especially if the former is somehow freed from the U.S. trade sanctions at a later time,” said TrendForce’s report.

In a previous report published shortly after Honor’s sale was announced, TrendForce predicted that the deal, along with the global chip shortage, meant Huawei would take just 4% of the market in 2021, compared to the 17% it held in 2019, and estimated 14% in 2020. Apple is expected to take away some market share from Huawei’s high-end smartphones, while Xiaomi, OPPO and Vivo will also benefit. TrendForce expects the newly spun-out Honor to take 2% market share in 2021.

8 investors discuss social gaming’s biggest opportunities

The gaming industry has had plenty of watershed moments in 2020 as consumer entertainment habits have shifted in response to the pandemic. One trend has been the crystallization of MMOs as social entertainment hubs that serve more needs for users than ever before.

Following my survey of gaming-focused investors on trends in the AR/VR world several months ago, I pinged a handful of investors to tap their thoughts on the shifting trends and opportunities in social gaming.

One thing that most investors expressed excitement around was the widening entertainment ambitions of social platforms, as concerts and movie screenings find homes on gaming platforms like Fortnite.

While evolving free-to-play mechanics continue to elevate the experience of single-player titles into something more living and breathing, platforms like Roblox have found areas for growth that seem more unique, developing into destinations for users to communicate and share.

“It’s where culture is created,” Madrona’s Daniel Li told TechCrunch.

Not all of the respondents shared the belief that a gaming platform like Fortnite would grow to become the next Facebook. General Catalyst’s Niko Bonatsos pointed to adjacent platforms like Discord or Twitch as the constants that would remain as consumers cycled through different platform ecosystems. Other pointed to the the still-disjointed experience switching between mobile and desktop experiences as a yet-to-be-solved stumbling block.

Building the metaverse and building a popular casual mobile game are two different things. Most investors I talked with emphasized how much the pace of scaling has accelerated across categories though with breakout hits rising faster than ever while disasters seem to grow evident just as quickly.

“I think that you look at Among Us, and Cyberpunk on the other side, anything can happen much faster and more extreme than it used to be just because of distribution,” Rogue VC’s Alice Lloyd George told TechCrunch.

Read below for the full answers; some responses have been edited for length and clarity.


Hope Cochran and Daniel Li, Madrona Venture Group

The idea that the next big social network will be an MMO seems to be a trendy take in the VC world, what are the roadblocks to this actually happening?

Daniel Li: Hope and I were trading some notes and part of our thesis is that gaming is the future of social and for Gen Z, gaming is replacing not just old games, but it’s replacing TV and Netflix. So instead of going to watch music videos on YouTube, you’re going to a concert in Roblox and that’s a social experience with your friend … instead of going to the mall, now you’re in Roblox. It’s where kids are hanging out and it’s where culture is created.

Hope Cochran: And in COVID, it’s the only place where they can hang out and I think the gaming industry has done a really fabulous job creating another social engagement that we need right now. I don’t want to focus too much on kids, but parents are becoming more accepting of their kids in the games because there is this social engagement and, for instance, I can see that my child is upstairs connecting with his four best friends. They log in together and they play. They normally might be out on a soccer field but they can’t right now so I think parents are becoming a little more comfortable saying, “Oh, he’s playing with his friends.”

Gaming has seemingly become a more “mainstream” area for investment, as someone who has been in the space a bit, what’s different about investing in the gaming sector?

HC: It’s very hard to find that balance between creative or understanding what might become a hit and a real business mind. So my experience has been that when you look into a gaming company as an investor, it’s actually more driven by math, stats and analytics, and then you have a core team who has the creative juices, so I try to look for that kind of dynamic.

So, who is developing what the users will love and who is analyzing it and how are they responding to what the users are loving. I do think there’s a point where a team develops a game and it’s mostly a creative process but then you have to kind of toggle to the analytics. It’s where the mathematicians meet the magicians and there needs to be a combination of that within every game.

What’s different about how popular games and MMOs are scaling these days? Have you seen any interesting growth hacks or strategies that seem promising?

DL: I think there are more and more of these cultural memes that just seem to come out of nowhere, like Among Us kind of just sat there for two years and streamers started picking it up and now it’s super popular. I’d say for nearly all of those, they’re going to be a social category of games, you don’t see a game like Cyberpunk come out of nowhere without any marketing dollars behind it.

So I do think one of those new channels is getting influencers to talk about your games, and typically I think for those it’s not actually the big influencers picking it up, it’s a whole bunch of small influencers all starting to play a game and have it start to build up steam that way. It’s more likely the Call of Duty’s that can hire the big streamers and pay them millions of bucks to play a new game, but I don’t think there’s a new to go-to-market for smaller studios around that.

How can MMOs, which feel like fundamentally active experiences, provide a better passive experience for users that may be more interested in the community than playing a first-person shooter or battle royale? How do games become more approachable to a wider audience?

DL: A lot of people are saying these single-player games aren’t really fun games anymore, they’re just like cinematic experiences. Like playing Cyberpunk for 60 hours versus binge-watching three TV series, it’s definitely a different experience. The thing that’s actually more interesting here is the virtual events that are happening inside these games. Thinking about what the next Twitch looks like, it’s probably some kind of experience where you’re inside the game doing something more passive.

Niko Bonatsos, General Catalyst


from Social – TechCrunch https://ift.tt/eA8V8J 8 investors discuss social gaming’s biggest opportunities Lucas Matney https://ift.tt/2LiNmNY
via IFTTT

Niantic buys competitive gaming platform Mayhem

Pokèmon Go creator Niantic has acquired a small SF gaming startup building a league and tournament organization platform to help gamers create their own communities around popular titles.

Mayhem was in Y Combinator’s winter 2018 batch and went onto raise $5.7 million in funding according to Crunchbase. Other backers include Accel, which led the startup’s Series A in 2018, Afore Capital and NextGen Venture Partners.

The startup’s focus has shifted quite a bit since its initial YC debut, when it announced a service called Visor that would analyze video of esports gameplay and coach users on how they could improve their performance. The company has seemed to shift its focus wholly to community tools to help gamers find matches and organize tournaments for games like Overwatch on its platform.

Terms of the acquisition weren’t disclosed by Niantic.

The “majority” of Mayhem’s team will be joining Niantic with the startup’s CEO Ivan Zhou landing in the company’s Social Platform Product team while the rest of the team joins Platform Engineering.

In a statement, Niantic asserts that the acquisition “reinforces our commitment to real-world social as the centerpiece of our mission.”

Read a deep dive of Niantic on Extra Crunch

Most of Niantic’s acquisitions of late have focused on augmented reality backend technologies so it’s interesting to see them buying tech that focuses on community organization.

Pokèmon Go continues to be Niantic’s cash cow though the company hasn’t seen the same levels of viral success with subsequent releases where organic growth hasn’t been quite as easy to come by. Buying a startup building community tools suggests the company is ready to bring in some outside tech to push their own efforts forward as they strive to create a broader platform for their AR ambitions and more standalone hits of their own.


https://ift.tt/3bfvE5W Niantic buys competitive gaming platform Mayhem https://ift.tt/38cra10

Monday, January 4, 2021

Looking to decarbonize the metal industry, Bill Gates-backed Boston Metal raises $50 million

Steel production accounts for roughly 8% of the emissions that contribute to global climate change. It is one of the industries that sits at the foundation of the modern economy and is one of the most resistant to decarbonization.

As nations around the world race to reduce their environmental footprint and embrace more sustainable methods of production, finding a way to remove carbon from the metals business will be one of the most important contributions to that effort.

One startup that’s developing a new technology to address the issue is Boston Metal. Previously backed by the Bill Gates-financed Breakthrough Energy Ventures fund, the new company has just raised roughly $50 million of an approximately $60 million financing round to expand its operations, according to a filing with the Securities and Exchange Commission.

The global steel industry may find approximately 14% of its potential value at risk if the business can’t reduce its environmental impact, according to studies cited by the consulting firm McKinsey & Co.

Boston Metal, which previously raised $20 million back in 2019, uses a process called molten oxide electrolysis (“MOE”) to make steel alloys — and eventually emissions-free steel. The first close of the funding actually came in December 2018 — two years before the most recent financing round, according to Tadeu Carneiro, the company’s chief executive.

Over the years since the company raised its last round, Boston Metal has grown from eight employees to a staff that now numbers close to 50. The Woburn, Massachusetts-based company has also been able to continuously operate its three pilot lines producing metal alloys for over a month at a time.

And while the steel program remains the ultimate goal, the company is quickly approaching commercialization with its alloy program, because it isn’t as reliant on traditional infrastructure and sunk costs according to Carneiro.

Boston Metal’s technology radically reimagines an industry whose technology hasn’t changed all that much since the dawn of the Iron Age in 1200 BCE, Carneiro said.

Ultimately the goal is to serve as a technology developer licensing its technology and selling components to steel manufacturers or engineering companies that will ultimately make the steel.

For Boston Metal, the next steps on the product road map are clear. The company will look to have a semi-industrial cell line operating in Woburn by the end of 2022, and by 2024 or 2025 hopes to have its first demonstration plant up and running. “At that point we will be able to commercialize the technology,” Carneiro said.

The company’s previous investors include Breakthrough Energy Ventures, Prelude Ventures and the MIT-backed “hard-tech” investment firm, The Engine. All of them came back to invest in the latest infusion of cash into the company along with Devonshire Investors, the private investment firm affiliated with FMR, the parent company of financial services giant, Fidelity, which co-led the deal alongside Piva Capital and another, undisclosed investor.

As a result of its investment, Shyam Kamadolli will take a seat on the company’s board, according to the filing with the SEC.

MOE takes metals in their raw oxide form and transforms them into molten metal products. Invented at the Massachusetts Institute of Technology and based on research from MIT Professor Donald Sadoway, Boston Metal makes molten oxides that are tailored for a specific feedstock and product. Electrons are used to melt the soup and selectively reduce the target oxide. The purified metal pools at the bottom of a cell and is tapped by drilling into the cell using a process adapted from a blast furnace. The tap hole is plugged and the process then continues.

One of the benefits of the technology, according to the company, is its scalability. As producers need to make more alloys, they can increase production capacity.

“Molten oxide electrolysis is a platform technology that can produce a wide array of metals and alloys, but our first industrial deployments will target the ferroalloys on the path to our ultimate goal of steel,” said Carneiro, the company’s chief executive, in a statement announcing the company’s $20 million financing back in 2019. “Steel is and will remain one of the staples of modern society, but the production of steel today produces over two gigatons of CO2. The same fundamental method for producing steel has been used for millennia, but Boston Metal is breaking that paradigm by replacing coal with electrons.”

No less a tech luminary than Bill Gates himself underlined the importance of the decarbonization of the metal business.

“Boston Metal is working on a way to make steel using electricity instead of coal, and to make it just as strong and cheap,” Gates wrote in his blog, GatesNotes. Although Gates did have a caveat. “Of course, electrification only helps reduce emissions if it uses clean power, which is another reason why it’s so important to get zero-carbon electricity,” he wrote.


https://ift.tt/eA8V8J Looking to decarbonize the metal industry, Bill Gates-backed Boston Metal raises $50 million https://ift.tt/3b6I3vM

Twitter acquires social podcasting app Breaker, team to help build Twitter Spaces

Twitter has acquired social broadcasting app Breaker, the companies announced today via a combination of blog posts and tweets. The deal will see Breaker’s team joining Twitter to help “improve the health of the public conversation” on the service, as well as work on Twitter’s new audio-based networking project, Twitter Spaces. The Breaker app, however, will shut down on January 15, 2021.

Breaker announced the acquisition on its company blog, explaining why it believes its team will be a good fit at Twitter.

“Here at Breaker, we’re truly passionate about audio communication and we’re inspired by the ways Twitter is facilitating public conversations for people around the world,” wrote Breaker CEO Erik Berlin. “We’re impressed by the entrepreneurial spirit at Twitter and enthusiastic about the new experiences that the team is creating.”

Breaker was founded in 2016 and is led by both CEO Berlin, previously the founder and CTO at social advertising company 140 Proof (which sold to Acuity), and CTO Leah Culver, who previously founded Pownce and Grove and co-authored web technologies OAuth and oEmbed.

The app had launched at a time when podcasts were still very much thought of as audio feeds and podcast apps as productivity tools — not experiences around which a community could be built. Breaker helped to change that perception by offering an app where users could like and comment on episodes, discover new podcasts by following friends, share favorite shows to social media and much more.

According to Culver’s tweet, she’ll be joining Twitter with a focus on Twitter Spaces, Twitter’s audio-based social networking product and Clubhouse rival. Spaces lets Twitter users chat in real time using voice instead of text, as they do today. The new product entered beta testing in December. Twitter is currently trying to work out not only the technical issues and bugs with the feature, but also the more complex issues that arise from hosting live audio, including moderation.

In a separate tweet, Twitter Engineering lead Michael Montano confirmed that Berlin, Culver and Breaker designer Emma Lundin will all be moving to Twitter as a result of the deal.

He also praised both Berlin and Culver’s entrepreneurial spirit as well as Culver’s push for open standards over the years.

Reached for comment, Twitter pointed to Montano’s tweet but offered no further details on the acquisition, price or broader plans.

Breaker says it will close in a matter of days its apps and services it built over the past years.

On January 15, 2021, Breaker will shut down for good. Up until that point, Breaker users will be able to export their OPML file to transfer their subscriptions to another podcasting app. Breaker recommends apps like Apple, Spotify, Stitcher, Overcast, Pocket Casts or Castro as an alternative. For those hosting a podcast on Breaker, these can be transferred elsewhere via the RSS feed.

The Breaker acquisition adds to a string of recent podcast M&A activity. But unlike recent deals that involved podcast content, Breaker’s sale is made up of staff and technology, not podcasts themselves. This maps to Twitter’s general focus on collating content from others instead of making its own.

The Breaker deal, with its unannounced price, feels modest. Which means that while the company’s exit to Big Tweet is another point on the board for podcasting companies finding their way to some sort of payout, it fits the general narrative that podcasting services and podcasting content only has so much value.

The acquisition follows other podcast content deals in recent weeks and months, including Amazon’s $300 million acquisition of Wondery, Sirius buying Stitcher for $300 million, not to mention all the content deals Spotify has picked up as of late.

That another podcast service sold for around $300 million has become a running joke. That number, while impressive-sounding to the individual, is not the sort of exit that venture capitalists target. The Breaker-Twitter tie-up, then, doesn’t push back on the idea that building a company focused on podcasting is to admit to a future that will have capped future upside.

Whether venture capitalists pull back from podcasting investments in 2021 is not yet clear, but Breaker’s sale does little to argue that private investors shouldn’t.

The real winner in the Breaker deal is Twitter, as it gains key talent as it enters what is shaping up to be a buzzy new market in 2021 for voice-based social networking — an idea whose time has come, perhaps, thanks to people being stuck at home amid a pandemic. Without conferences and parties to attend, many went in search of better ways to connect online.

But it remains to be seen if Twitter — a service that has publicly struggled with online toxicity and moderation failures — will be able to make audio networking a safe place for users to chat, or if it will amplify Twitter’s existing challenges in these areas. It also remains to be seen if voice-based networking will have a future in a reopened, post-COVID world where we can once again meet others in real-world, public places, instead of Twitter Spaces.


from Social – TechCrunch https://ift.tt/2DJbsOs Twitter acquires social podcasting app Breaker, team to help build Twitter Spaces Sarah Perez https://ift.tt/3nfBFoD
via IFTTT

BadVR is using government grants to build a business that’s independent of venture capital

When the Los Angeles-based extended reality data visualization company BadVR first heard that one of its earliest benefactors, Magic Leap, was about to shed 1,000 jobs and was fighting for its life, the young startup was unfazed.

Despite the very public ties that BadVR had to Magic Leap, as one of the enterprise applications on the platform, the startup was more insulated than other businesses from the pivot away from consumer-focused apps.

The first step was finding money from the government’s Paycheck Protection Program to get more capital coming in and maintaining its headcount. Eventually, the company managed to land additional financing in the form of a $1 million grant from the National Science Foundation.

It’s the second grant that the company has taken from the NSF and is an example of how startups can turn to government funding for capital and avoid some of the pitfalls of fundraising from venture capital.

To be sure, even Magic Leap’s trip to the brink of collapse wouldn’t have been that bad for BadVR, which makes enterprise applications for extended reality devices.

What the Magic Leap story shows is that companies don’t need to take venture capital to make it. Indeed, as costs come down for equipment and remote work democratizes access to a country that’s still teeming with engineering talent, thrifty startups can get the capital they need from government sources and corporate innovation grants.

That’s how BadVR got most of its $3.5 million in financing. Some money came from a grant from BadVR, while at least $1.25 million has come from the government in the form of two National Science Foundation cooperative agreements through the Small Business Innovation Research financing mechanisms.

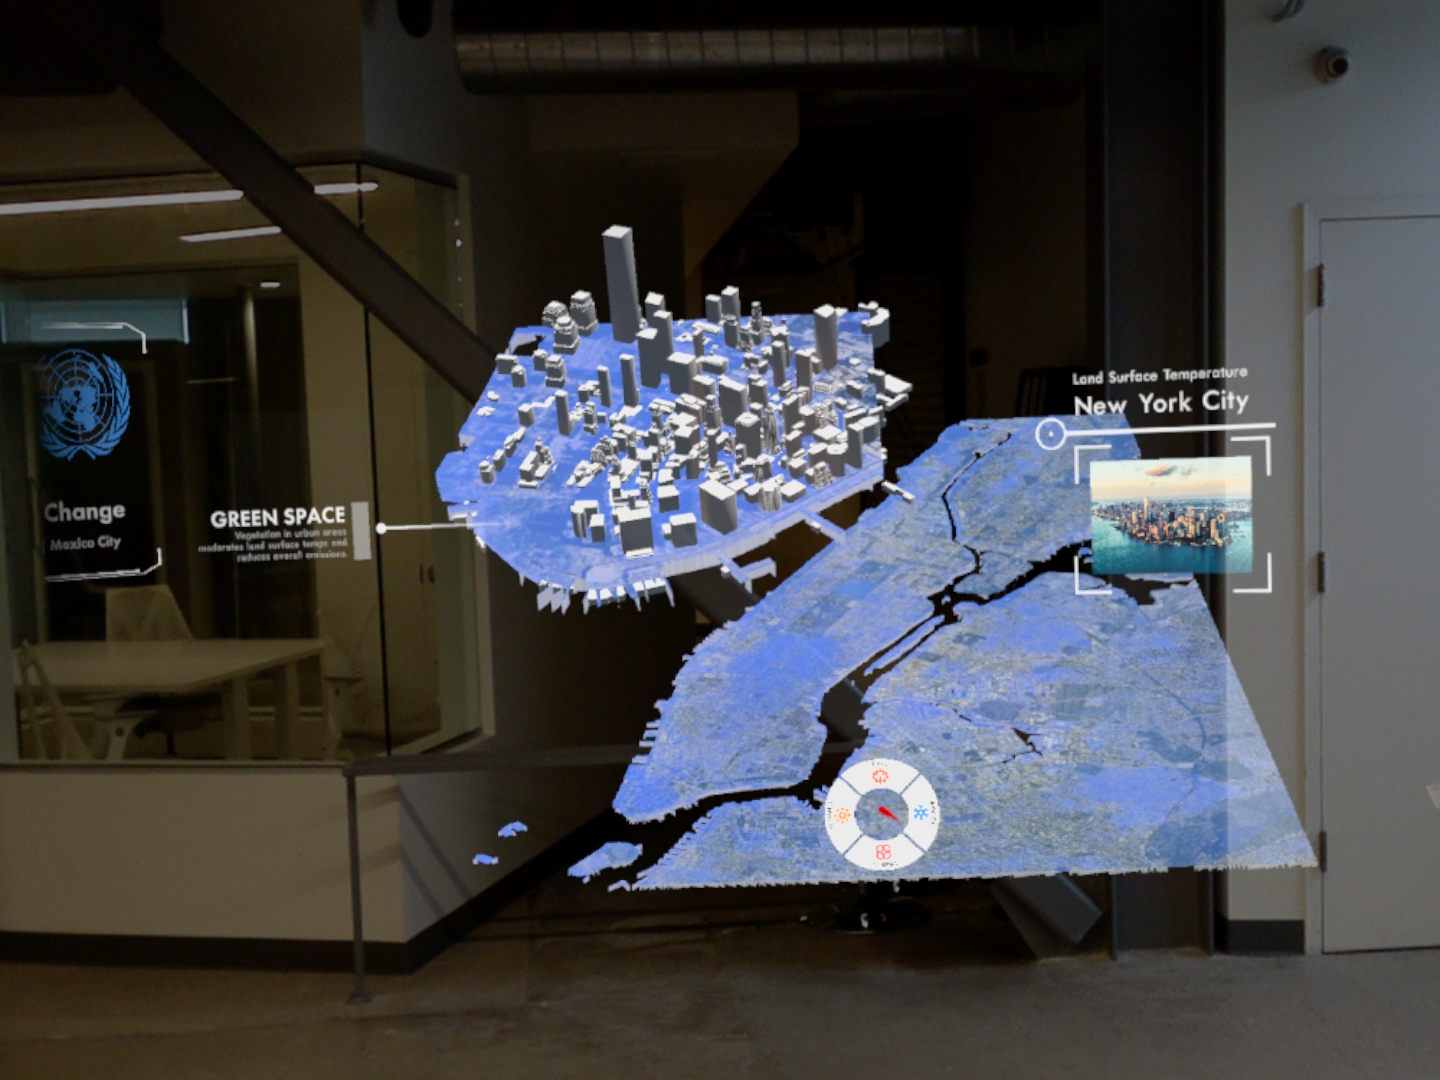
A headset capture of BadVR’s climate change application, built for the Magic Leap One headset. Image Credits: BadVR

BadVR uses virtual and augmented reality tools to visualize geospatial data for a range of government and commercial applications. The startup’s tech is already being used by big telecom companies to accelerate the planning and deployment of 5G networks. And, within the public safety sector, the company’s tech is used to improve situational awareness for first responders and to reduce training, staffing and operational costs.

“Society has become aware of the power of data and the impact it has on our daily lives. It’s critically important that we make the access of data easy to every organization, regardless of technical skill level or background,” said Suzanne Borders, the chief executive and founder of BadVR, in a statement. 

For Borders, the key to tapping government funding is all about proper advance planning. “Those take a long time,” Borders said. “When you get awarded them, you’re looking at a year’s worth of effort. [Our grant] was a testament to us planning for that about a year ago.”

These grants are typically milestone-based, so as long as BadVR was hitting its targets, it could be fairly assured that the money would be there.

“NSF is proud to support the technology of the future by thinking beyond incremental developments and funding the most creative, impactful ideas across all markets and areas of science and engineering,” said Andrea Belz, Division Director of the Division of  Industrial Innovation and Partnerships at NSF. “With the support of our research funds, any deep technology startup or small business can guide basic science into meaningful  solutions that address tremendous needs.”  

Other government competitions are providing the company with additional non-dilutive cash and a chance to kick the tires on new capabilities.

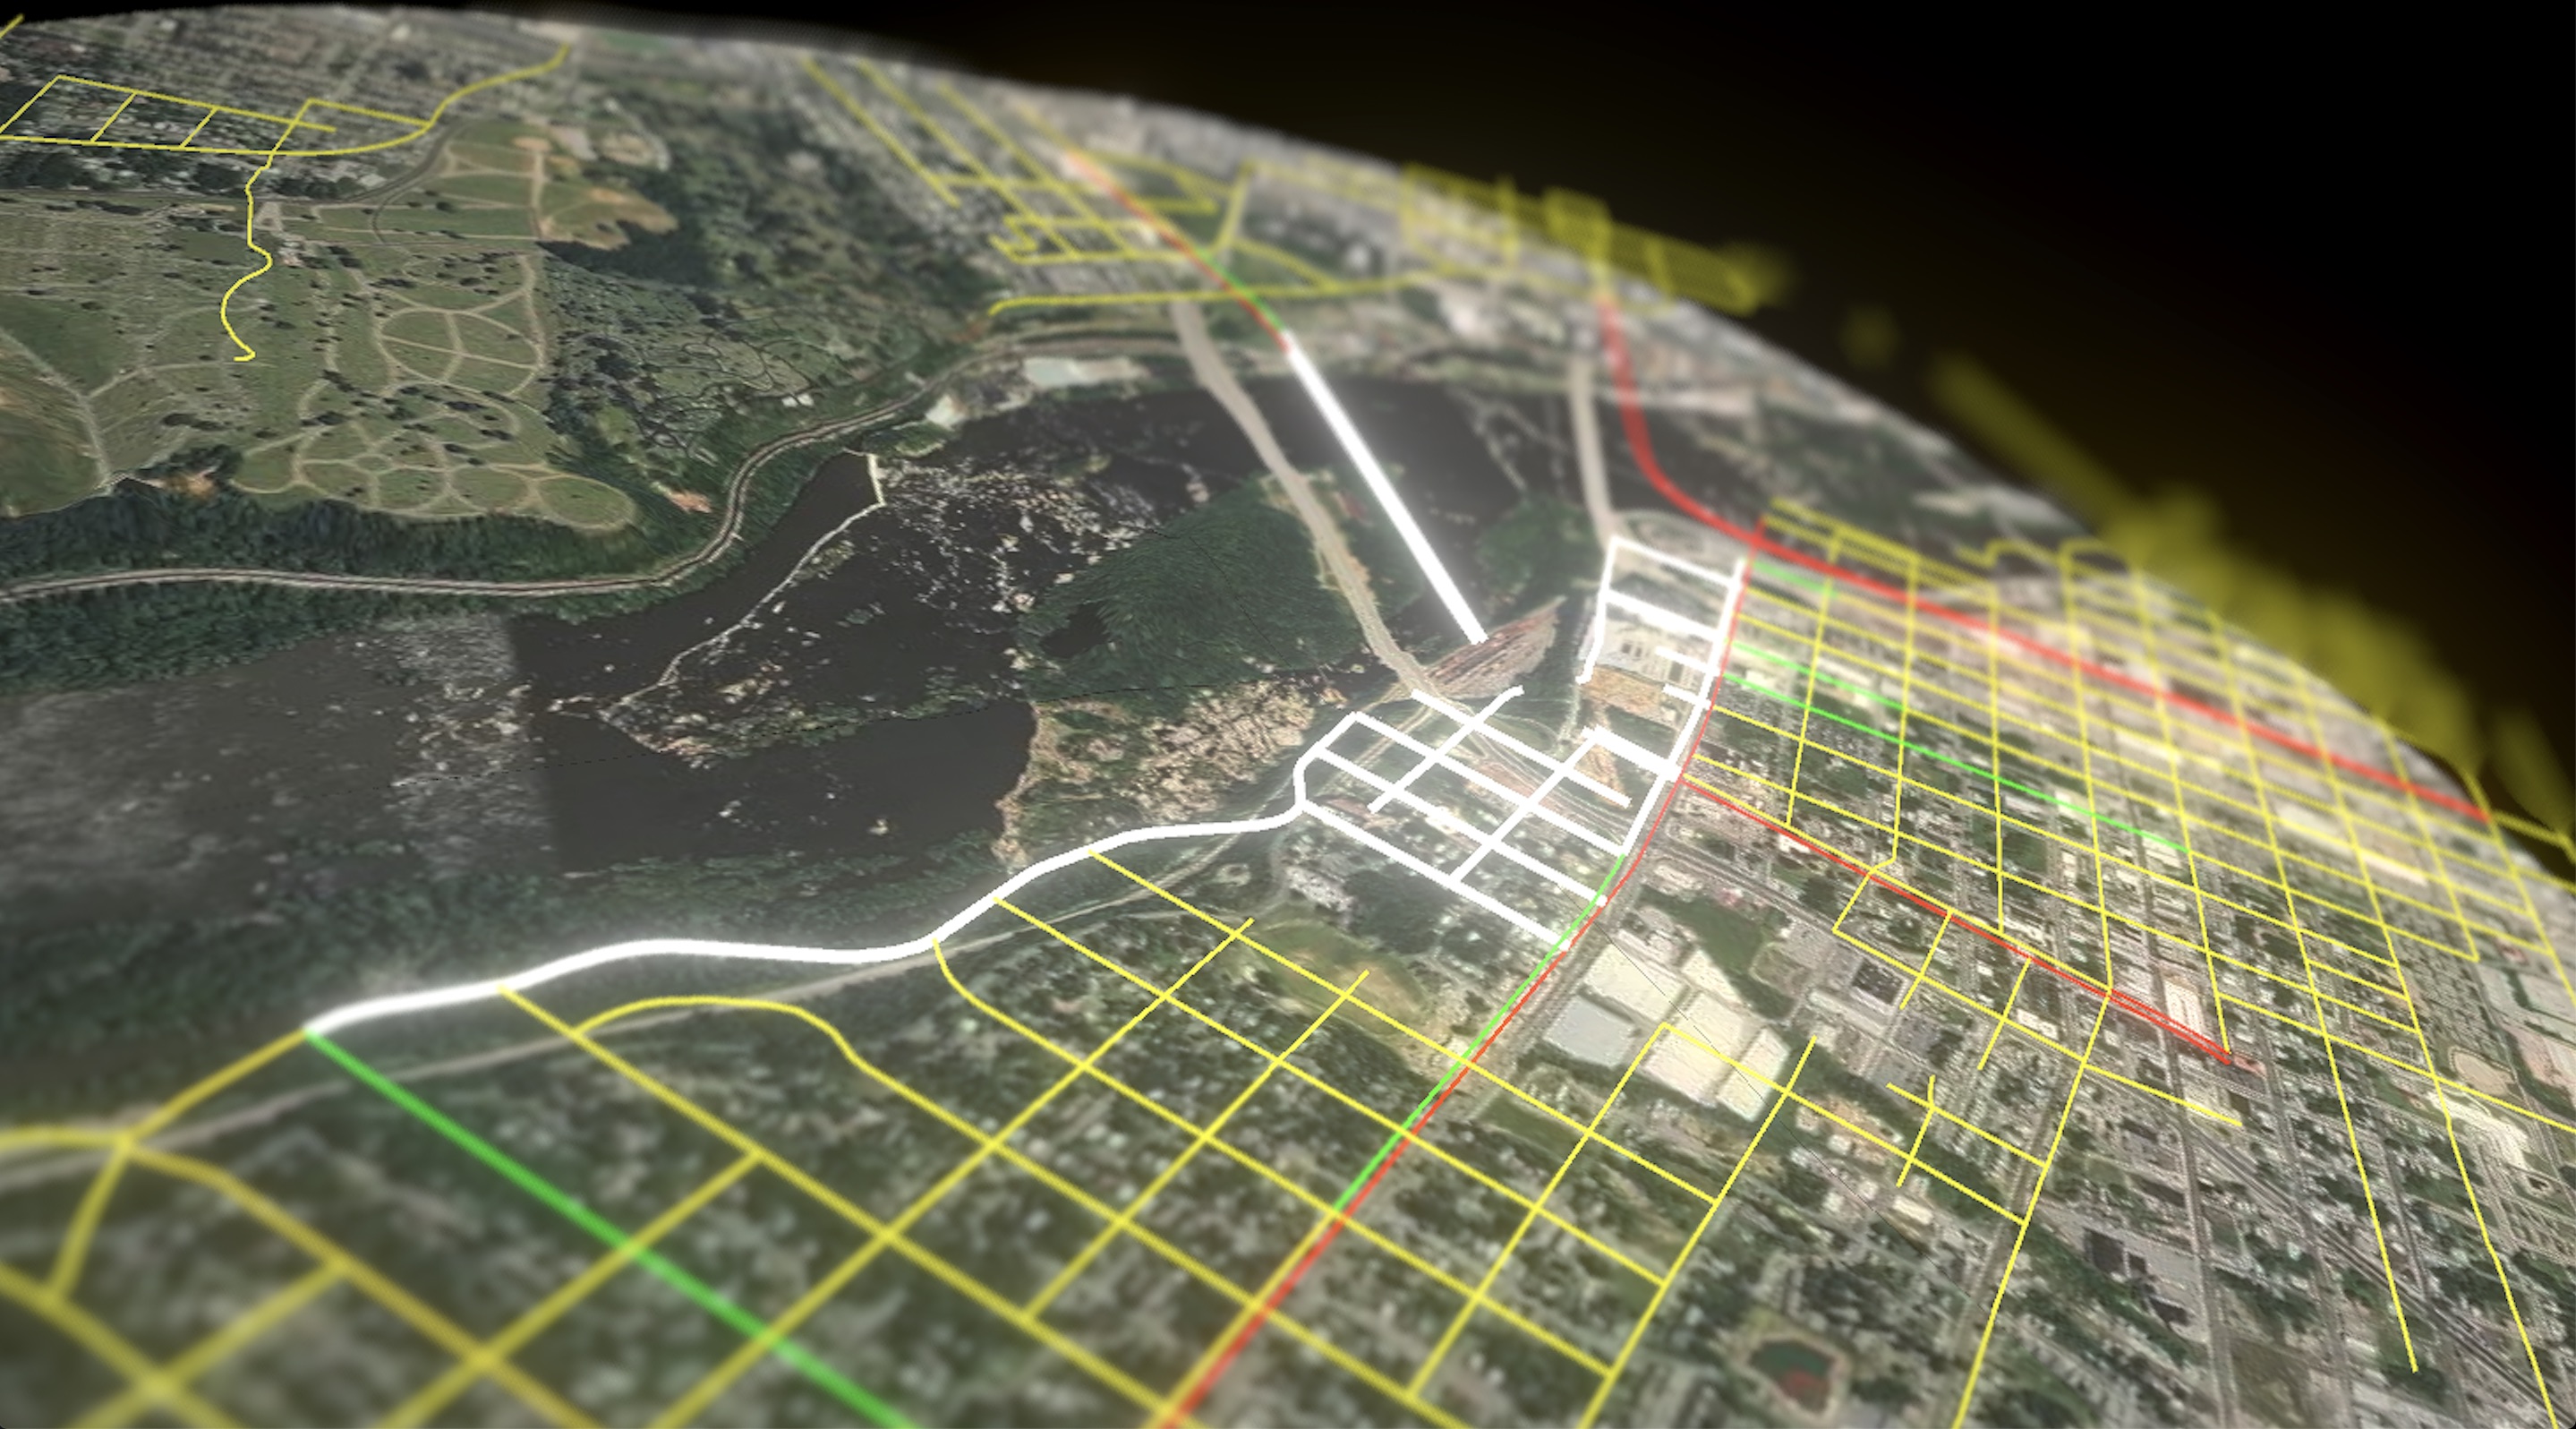
A capture from BadVR’s augmented reality geospatial data environment, which allows users to visualize multiple live and historical data sets via overlays relevant to their environment. Image Credits: BadVR

That has translated into traction for the company’s Augmented Reality Operations Center. The AROC is a new offering for the product that visualizes data for first responders. Through a challenge hosted by the National Institute of Standards and Technology, BadVR was able to work with the Eureka, Missouri Fire Department to develop a prototype for a specific emergency situation.

It’s an evolution of an early product the company had developed where enterprises can create digital twins of their factories or stores in virtual reality and do a walk-through to examine different conditions.

The visualization work that BadVR does isn’t necessarily all geo-spatial. The company can take all kinds of data and integrate that into an environment that makes the data easier to see. Borders sees the company’s services extending into creating all kinds of collaborative environments for companies.

“The system highlights things that are important to look at,” Borders said. “It’s virtualizing the data visualization experience and bringing it into an immersive environment — and building a more collaborative aspect to that experience.”

Since the COVID-19 pandemic has forced businesses across the country to operate virtually, Borders said the demand for the kinds of products her company is building — with the government’s help — has only increased.

“That’s been due to increased demand for remote collaboration tools,” Borders said. “We’ve had increased interest in people across the board — but tools that have remote collaboration capabilities — and bring people together to one immersive data experience… those are taking off.”


https://ift.tt/395zkYr BadVR is using government grants to build a business that’s independent of venture capital https://ift.tt/2WWHn3W

How to convert customers with subscription pricing

The lure of subscription pricing is the guarantee of recurring revenue for your business. Once a customer flips the switch to turn on your subscription, it’s easy money:

  • Easy to recognize your revenue.
  • Easy to determine your margins and profits.
  • Easy to enhance your product and extend that revenue out for months, even years.

While that’s true, converting a subscription customer isn’t as simple as flipping a switch. You can build a platform, launch with fanfare, offer all sorts of incentives and trials to attract potential customers — and watch as they disengage and lapse into limbo.

Contrary to popular belief, subscription pricing doesn’t work because of the lower price point that a monthly installment allows.

That’s the actual guarantee that comes with subscription pricing, which will happen unless you cultivate a funnel that catches potential subscribers as soon as they learn about your product and follows them until their very last sign-in.

I built my first subscription-model product in 1999. I’m currently in early-access on my latest, and I’ve launched a bunch more along the way.

While the customer dynamic has changed over the last 20 years, the conversion process has not. In fact, it’s actually gotten easier to convert and retain customers through the subscription funnel.

Here’s what I’ve learned.

Why subscription pricing works

Subscription pricing is a hot trend in just about every business in every industry. Pay-as-you-go is the new normal from software to retail to service.

In my mind, the major shift occurred when mobile phones started pricing unlimited usage per period instead of fixed or cost per minute. Once usage limits were removed, use cases exploded and the promise of a truly mobile computer was finally realized.

Makers of all stripes learned that lesson: From razors to video streaming to accounting software, pricing models have emerged that focus on time periods instead of units.

But contrary to popular belief, subscription pricing doesn’t work because of the lower price point that a monthly installment allows. It’s effective because a subscription reorients each customer’s mind from product function to value proposition.

I don’t care what kind of German engineering went into my razor blades, as long as I have working blades when I need them.

As an entrepreneur, you probably use at least one digital subscription service to build your own product and company, if not several. In fact, just to get to the MVP of my new project, I subscribed to AWS, MailChimp, Zapier and Bubble. I’m still on the free tier of a few more services for some lower-priority features. There’s a few more I quit or never tried.

Thus, you know that value prop plays a big part of whether the customer will pay and stay. So reinforcing your value proposition should play a big part in every level of your customer funnel.

You must catch and track customers to be effective

A subscription-pricing model without an ability to track the steps in the conversion funnel will result in all the headaches of subscription pricing without any of the benefits.


https://ift.tt/eA8V8J How to convert customers with subscription pricing https://ift.tt/3ncx4U3

blogger better Headline Animator