l
l
blogger better. Powered by Blogger.

Search

Labels

blogger better

Followers

Blog Archive

Total Pageviews

Labels

Download

Blogroll

Featured 1

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 2

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 3

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 4

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Featured 5

Curabitur et lectus vitae purus tincidunt laoreet sit amet ac ipsum. Proin tincidunt mattis nisi a scelerisque. Aliquam placerat dapibus eros non ullamcorper. Integer interdum ullamcorper venenatis. Pellentesque habitant morbi tristique senectus et netus et malesuada fames ac turpis egestas.

Monday, June 14, 2021

Fraud protection startup nSure AI raises $6.8M in seed funding

Fraud protection startup nSure AI has raised $6.8 million in seed funding, led by DisruptiveAI, Phoenix Insurance, AXA-backed venture builder Kamet, Moneta Seeds and private investors.

The round will help the company bolster the predictive AI and machine learning algorithms that power nSure AI’s “first of its kind” fraud protection platform. Prior to this round, the company received $550,000 in pre-seed funding from Kamet in March 2019.

The Tel Aviv-headquartered startup, which currently has 16 employees, provides fraud detection for high-risk digital goods, such as electronic gift cards, airline tickets, software and games. While most fraud detection tools analyze each online transaction in an attempt to decide which purchases to approve and decline, nSure AI’s risk engine leverages deep learning techniques to accurately identify fraudulent transactions.

NSure AI, which is backed by insurance company AXA, said it has a 98% approval rating on average for purchases, compared to an industry average of 80%, allowing retailers to recapture nearly $100 billion a year in revenue lost by declining legitimate customers. The company is so confident in its technology that it will accept liability for any fraudulent transaction allowed by the platform.

Founders Alex Zeltcer and Ziv Isaiah started the company after experiencing the unique challenges faced by retailers of digital assets. The first week of their online gift card business found that 40% of sales were fraudulent, resulting in chargebacks. The founders began to develop their own platform for supporting the sale of high-risk digital goods after no other fraud detection service met their needs.

Zeltcer, co-founder and chief executive, said the investment “enables us to register thousands of new merchants, who can feel confident selling higher-risk digital goods, without accepting fraud as a part of business.”

NSure AI, which currently monitors and manages millions of transactions every month, has approved close to $1 billion in volume since going live in 2019.


https://ift.tt/eA8V8J Fraud protection startup nSure AI raises $6.8M in seed funding https://ift.tt/2TuxI6a

How one founder is bringing the global corporate security industry out of the dark ages

When Cory Siskind finished school, she was dropped into a high-stakes job helping large multinational corporations manage their operational security in Mexico City, with almost no relevant lived experience. Eventually, she realized that this was more or less par for the course in the corporate security field, which lagged behind other mission-critical enterprise services, like information security.

The industry still relied on recent grads doing manual work like combing through blogs and local news reports, and on security industry veterans with contacts on the ground to build a sort of ‘whisper network’ of ground truth. Those things are obviously still valuable, but advancements in technology mean that there are many, many more sources of information that can provide valuable insight into the security situation in any particular country, region or even neighborhood, and machine learning has progressed to the point where it can do a lot of the legwork involved in helping analysts parse the data.

Cory tells us all about how she came to the conclusion that Base Operations needed to be built to bring modern tech to bear on the capabilities gap she saw in how companies manage their global security footprint, and how she set out getting the skills needed to build her startup as a sole founder. We talk about the challenges of fundraising in an area where most traditional VCs likely feel out of their depth, and building a sales operation that can handle big clients even very early on tin her startup’s life.

We loved our time chatting with Cory, and we hope love yours listening to the episode. And of course, we’d love if you can subscribe to Found in Apple Podcasts, on Spotify, on Google Podcasts or in your podcast app of choice. Please leave us a review and let us know what you think, or send us direct feedback either on Twitter or via email. And please join us again next week for our next featured founder.


https://ift.tt/eA8V8J How one founder is bringing the global corporate security industry out of the dark ages https://ift.tt/3gjCIUi

Could Claap, an asynchronous video meetings platform, end the tyranny of Zoom calls?

Because of the pandemic, we’re all a lot more familiar with remote working than we used to be, whether we like it or not. But the remote tools of the pre-pandemic era — Slack, Trello, Zoom, Asana, etc., etc., etc. — are, if we admit it to ourselves, barely scratching the surface of what we really need to be productive. Luckily a new era of remote-working tools is fast emerging. As I recently tweeted, we need to think far more in asynchronous terms if remote working is to be productive (and healthy!), long term.

Older tools can offer asynchronous collaboration, but a new wave of tools is coming. Loom, for instance, is one-way video for “show and tell”. It’s raised $203.6 million — however, it has a drawback: it doesn’t have many collaboration features.

Now a new European startup hopes to address this.

Claap, an asynchronous meeting platform with video and collaboration, thinks it might have part of the solution, and a private beta launch is planned for this month.

It’s now raised $3 million in pre-seed funding from LocalGlobe, Headline, E.Ventures, Kima Ventures, and angels including Front co-founder Mathilde Collin, Oyster co-founder Tony Jamous, Nest and GoCardless founder Matt Robinson and Automattic’s head of product Aadil Mamujee. It also includes a group of 30 angels such as Ian Hogarth (Songkick), Olivier Godement (Stripe), Roxanne Varza (Station F), Chris Herd (FirstBase), Xavier Niel (Kima) and Shane Mac (investor in Remote).

We all now know that what were previously small catch-ups are now 30-minute Zoom calls, which are pointless. “Asynchronous meetings” could be the way forward.

Claap says its product allows employees to record a short video update on a topic, allow others to comment on the relevant part, and set a due date for team members to respond. Colleagues then view the video and respond in their own time. Claap bills itself as the remote working equivalent of the “quick hallway catch-up”. It integrates with other workplace tools such as Trello or Jira so that when a decision is made on a project, it’s recorded for everyone on the team to see and refer back to. A subscription model is planned which will have a sliding scale depending on team size.

Because it doesn’t require real-time interaction, you don’t need to find a time that suits everyone for a meeting, so in fact the “meeting” sort of disappears. Instead, the platform creates a space for feedback and iterations.

Founders Robin Bonduelle and Pierre Touzeau looked at solutions already adopted by companies such as Automattic, and GitLab. Touzeau was previously at 360Learning, which employed a strict limiting policy for meetings. Bonduelle has 10 years of product management experience, working at various startups and scaleups including Ogury where he was VP of Product, and Rocket Internet. He developed asynchronous communication habits while managing 50 people across four countries and time zones. Touzeau has worked for businesses including L’Oréal and 360Learning, where he was most recently VP of Marketing.

However, asynchronous communication is not always perfect. As we know, emails and Slack messages can go unread. Video MIGHT be the solution.

Robin Bonduelle, co-founder and CEO at Claap, said: “After a year of working remotely, people are realizing the benefits of not working in an office but at the same time grappling with one of its worst consequences: back-to-back video meetings. A query that in the office would take five minutes to solve now takes at least 30, leaving everyone more exhausted in the process. Claap is designed to solve this issue, allowing colleagues the tools to keep them engaged and connected but without taking up all their time. It’s a new meeting format that allows people to make quick decisions.”

Touzeau said: “Meetings are a necessary part of working, but it doesn’t need to be your entire day. Asynchronous meetings are the key to freeing up our calendars but making sure work still gets done and deadlines are met. We’re excited by the potential Claap has to empower people to work from anywhere.”

George Henry, general partner at LocalGlobe, said: “We were impressed with Robin and Pierre’s vision and the potential for Claap to allow employees to connect on a project when they need to and facilitate the ability to work from anywhere.”

Jonathan Userovici, partner at Headline, said: “Zoom may have been the go-to enterprise app over the past 12 months but for the thousands of businesses that are now going to be remote-first, video conferencing alone won’t be enough to keep teams connected and get work done. Claap is the challenger tool to end video-calling fatigue.”


https://ift.tt/eA8V8J Could Claap, an asynchronous video meetings platform, end the tyranny of Zoom calls? https://ift.tt/2TrevST

The Pill Club takes on primary care with $41.9M in fresh funding

In January, former Uber executive Liz Meyerdirk announced that she has taken over as chief executive of The Pill Club. The company, which offers an online birth control prescription and delivery service to hundreds of thousands of women, had hit record revenues, crossing $100 million in annual run rate for the first time in its 4-year history.

She found the bridge between ride-sharing to healthcare to be smoother than some might expect, saying that she focused on how to apply technology “to logistics for an everyday use case, [to know] how that simplifies your everyday life.”

Now, six months into her new job, Meyerdirk announced that her company has raised more capital to capitalize off of the momentum in women’s health right now. The Pill Club announced today that it has raised a $41.9 million Series B extension round led by Base 10. Existing investors including ACME, Base10, GV, Shasta Ventures and VMG participated in the round, as well as new investors including Uber’s Dara Khosrowshahi and Honey’s George Ruan and iGlobe.

The extension round comes over 2 years after the company announced its initial Series B investment, a $51 million financing led by VMG Partners. After reportedly being valued at $250 million, the company declined to provide its latest valuation, other than saying that the extension was an up-round.

When a customer joins The Pill Club, they are given a medical questionnaire and a digital form to input personal information. The company gives them a sense of how much the service will cost, and if the price works, it connects them to a nurse either live or via text.

“In a happy case, you can see a nurse immediately, “ she said. “Obviously if it’s midnight, we haven’t figured that out yet.” The nurse walks though different options, since, Meyerdirk added, “contraception is not one size fits all.”

Once a customer makes a decision, The Pill Club can then prescribe birth control through their own pharmacy, which will be delivered to their door within two or three days.

The Pill Club launched in 2016 with an at-home delivery service of birth control. Between 2016 and January 2021, it launched in 43 states plus the District of Columbia. It has added 5 new states in the past six months, and plans to get to 50 states by the end of 2021.

The company makes money from a medical visits, insurance reimbursement for prescription drugs, and cash patients who aren’t covered by insurance.

The chief executive views a big part of its value proposition as embedding with existing insurance plans of its customers, including Medi-CAL and Family PACT. In the last three months, 16% of The Pill Clubs’ new patients were on Medicaid.

“You’ve got companies like Oscar [Health] that are reimagining health insurance, and you’ve got Ro, Hims and Hers, who are [taking] cash as a primary…way to serve..patients,” she said. “That’s fantastic for those who can afford it, but for us, because so much of our value system is around access to equity, we believe everyone should have the right to get access to birth control.”

The company believes that it has to work within the system of insurance to have true innovation.

“Telemedicine that ignores the reality of insurance is always going to have a limited piece of the pie,” a spokesperson from the company said said. “Cash-only systems simply aren’t a product built for a scale. A truly innovative healthcare platform exists within the realities of the system.”

By women, for women

Long-term, the Pill Club wants to replace the old model of going to a primary care provider for annual visits with ongoing care for women.

“I’m generally healthy [but] I actually do have questions on mammograms…colonoscopies, or anything,” Meyerdirk said. “And being able to have a person other than my mom” to talk to that doesn’t require a trip to the doctor or urgent care, is the gap that The Pill Club wants to fill.

“We think it’s too good to be true, when we actually get what we deserve,” Meyerdirk said when describing women’s health. Part of her goal going forward is to think bigger, beyond contraception, and figure out how The Pill Club could bring a digital refresh to other areas of women’s health.

In March, the company launched a dermatology pilot, and also expanded its 2020 period care pilot. A portion of the new capital is earmarked toward launching new services for its members.

The Pill Club also shared the diversity metrics of its 350-person staff as part of its announcement.

The Pill Club has 72% of employees identifying as women, and 28% of employees identifying as male. The executive leadership similarly sees predominantly women, with the ratio being 62.5% women and 37.5% male. As for racial diversity, the overall company identifies as 33% white, 19% Asian, 16% Hispanic or Latino and 14% Black or African American, with 13% of employees declined to identify.

“We’re by women for women,” Meyerdirk said. “It’s very, very different when you’re by men, for women.” Her appointment came as The Pill Club’s founder and former chief executive officer Nick Chang, stepped down from day to day operations. He didn’t take a board seat, but does still have shares in the company.

Liz Meyerdirk, chief executive of The Pill Club.

The wave of prescription, for-delivery medication is only getting bigger, with The Pill Club joined by startups such as Nurx and Simply Health, and bigger corporations such as Walmart and Amazon.

“The idea of creating more choice and flexibility across healthcare is long overdue,” she said. “Everyone deserves to have great options when they consider who can best address their daily needs.”

Editor’s note: A prior version of this story noted that The Pill Club does birth control for pick up. This is incorrect. It delivers birth control through its own pharmacies. A correction has been made to reflect this change.  


https://ift.tt/35gffwZ The Pill Club takes on primary care with $41.9M in fresh funding https://ift.tt/3xl0TY1

Yana’s mental health tool for Spanish speakers nears 5 million users

Andrea Campos has struggled with depression since she was 8 years old. Over the years, she’s tried all sorts of therapies — from behavioral to pharmacotherapy.

In 2017, when Campos was in her early 20s, she learned to program and created a system to help manage her mental health. It started as a personal project but as she talked to more people, Campos realized that many others might benefit from the system as well.

So, she then built an application to provide access to mental health tools to Spanish-speaking people and began testing it with a small group of people. At first, Campos herself was her own chatbot, texting with users who were tired of dealing with depression.

“During the month, I was pretending I was an app, and would send these people a list of activities they had to complete during the day, such as writing in a gratitude journal, and then asking them how those activities made them feel,” Campos recalls.

Her thinking was that sometimes with depression and anxiety comes “a lot of avoidance,” where people resist potential treatment out of fear.

The results from her small experiment were encouraging. So, Campos set out to conduct a bigger sample of experiments, and raised about $10,000 via crowdfunding campaign. With that money, she hired a developer to build a chatbot for her app, which was mostly being used via Facebook Messenger.

Then an earthquake hit Mexico City and that developer lost everything — including his home and computer — and had to relocate.

“I was left with nothing,” Campos says. But that developer introduced her to another, who disappeared with his payment, and again, left Campos, “with nothing.”

“I realized at the beginning of 2019, I was going to have to do this by myself,” Campos said. So she used a site that she described as a “Wix for chatbots,” and created one herself.

After experimenting with the app with a sample of 700 people, Campos was even more encouraged and raised an angel round of funding for Yana, the startup behind her app. (Yana is an acronym for “You Are Not Alone.”) By early 2020, with just three months of runway left, she pivoted to create an app with chatbot integration that wasn’t just limited to use via Facebook Messenger.

Campos ended up launching the app more broadly during the same week that her city in Mexico went into quarantine.
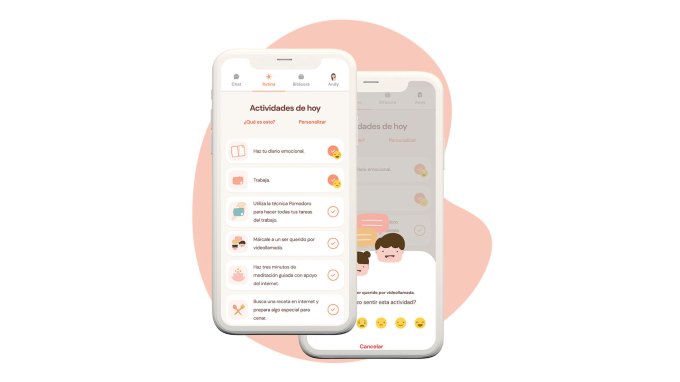
Image Credits: Yana

At first, she said, she saw “normal, steady growth.” But then on Oct. 10, 2020, Apple’s App Store highlighted Yana for International Mental Health Day, and the response was overwhelming.

“It was also my birthday so I was at a spa in a nearby town, relaxing, when I started hearing my cell phone go crazy,” Campos recalls. “Everything went nuts. I had to go back to Mexico City because our servers were exploding since they were not used to having that kind of volume.”

As a result of that exposure, Yana went from having around 80,000 users to reaching 1 million users two weeks later. Soon after that, Google highlighted the app as one of best for personal growth in 2020, and that too led to another spike in users. Today, Yana is about to hit the 5 million-user mark and is also announcing it has raised $1.5 million in funding led by Mexico’s ALLVP, which has also invested in the likes of Cornershop, Flink and Nuvocargo.

When the pandemic hit last year, six of Yana’s 9-person team decided to quarantine together in a “startup house” in Cancun to focus on building the company. Earlier this year, the company had raised $315,000 from investors such as 500 Startups, Magma and Hustle Fund. The company had pitched ALLVP, who was intrigued but wanted to wait until it could write a bigger check. 

That time is now, and Yana is now among the top three downloaded apps in Mexico and 12 countries including Spain, Chile, Ecuador and Venezuela.

With its new capital, Yana is planning to “move away from the depression/anxiety narrative,” according to Campos.

“We want to compete in the wellness space,” she told TechCrunch. “A lot of people were looking for us to deal with crises such as a breakup or a loss but then they didn’t always see a necessity to keep using Yana for longer than the crisis lasted.”

Some of those people would download the app again months later when hit with another crisis.

“We don’t want to be that app anymore,” Campos said. “We want to focus on whole wellness and mental health and transmit something that needs to be built every single day, just like we do with exercise.”

Moving forward, Yana aims to help people with their mental health not just during a crisis but with activities they can do on a daily basis, including a gratitude journal, a mood tracker and meditation — “things that prevent depression and anxiety,” Campos said.

“We want to be a vitamin for our soul, and keeping people mentally healthy on an ongoing basis,” she said. “We also want to include a community inside our application.”

ALLVP’s Federico Antoni is enthusiastic about the startup’s potential. He first met Campos when she was participating in an accelerator program in 2017 and then again recently.

The firm led Yana’s latest round because it “wanted to be on her team.”

“She [Campos] has turned into an amazing leader, and we realized her potential and strength,” he said. “Plus, Yana is an amazing product. When you download it, it’s almost like you can see a soul in there.”


https://ift.tt/3iHkxtc Yana’s mental health tool for Spanish speakers nears 5 million users https://ift.tt/3vqBf2C

The Nubank EC-1

Brazil is a country riven with economic contradictions. It has one of the largest and most profitable banking industries in Latin America, and is among the world’s most developed financial markets. Financial transactions that would take days to process in the United States through ACH happen instantaneously in Brazil. This sophistication, however, masks a backward state of affairs plagued by appalling customer service, exorbitant fees and lack of banking access for many.

The country’s financial system is volatile and often leaves its citizens with few or no alternatives. According to an HBS case study, “in December 2018 the interest rate in Brazil for corporate loans was 52.3%, for consumer loans it was 120.0% and for credit card indebtedness it was 272.42%.” Those rates are many multiples higher compared to figures in neighboring countries.

Brazil’s banking system is a massive market, and one ill-served by incumbents. If someone could thread the needle of product development, strategy and political horse trading required to build a bank in a country where it is nearly impossible for foreigners to own or invest in a bank, it would be one of the great startup and economic success stories of this century.

Nubank is on its way to realizing that objective. Its story is one of unmitigated success, even by the standards of our EC-1 series on high-flying companies and their hard-learned lessons. Just last week, this Brazilian credit card and banking fintech raised a $750 million round led by Berkshire Hathaway at a $30 billion valuation, becoming one of the most valuable startups in the world. It has 40 million users across Brazil, as well as Mexico and Colombia.

Yet, it’s a startup with a CEO and co-founder who isn’t Brazilian, didn’t speak the local language of Portuguese, hadn’t started a company before, and didn’t really know a lot about banking to begin with. This is a story of how raw execution, a “faster, faster” mentality and a fanaticism for making customer experience as enjoyable as a trip to Disney World can completely change the history of an industry — and country — forever.

Our lead writer for this EC-1 is Marcella McCarthy. McCarthy, who spent significant time in Brazil growing up and is trilingual in English, Spanish and Portuguese, has been covering the LatAm and Miami ecosystems for TechCrunch with an eye to the disruption underway in these interconnected regions. The lead editor for this package was Danny Crichton, the assistant editor was Ram Iyer, the copy editor was Richard Dal Porto, and illustrations were drawn by Nigel Sussman.

Nubank had no say in the content of this analysis and did not get advance access to it. McCarthy has no financial ties to Nubank or other conflicts of interest to disclose.

The Nubank EC-1 comprises four main articles numbering 9,200 words and a reading time of 37 minutes. Here’s what’s in the bank:

We’re always iterating on the EC-1 format. If you have questions, comments or ideas, please send an email to TechCrunch Managing Editor Danny Crichton at danny@techcrunch.com.


https://ift.tt/eA8V8J The Nubank EC-1 https://ift.tt/3xeujqG

How contrarian hires and a pitch deck started Nubank’s $30 billion fintech empire

For most startups, the hardest early challenge is identifying a market and a product to serve it. That wasn’t the case for Nubank CEO David Velez, who understood the massive potential for success if he could break into Latin America’s most valuable economy with even a moderately modern banking offering.

Instead, the challenge was how to rebuild the concept of a bank in a country where banking is widely hated, all while the incumbents heavily entrenched with the state worked to block every move.

Nubank knew its market and geography, and through tenacious fundraising, inventive marketing and product development, and a series of contrarian hires, Velez and his team stripped bare the morass of Brazilian banking to build one of the world’s great fintech companies.

The challenge was how to rebuild the concept of a bank in a country where banking is widely hated, all while the incumbents heavily entrenched with the state worked to block every move.

In the first part of this EC-1, I’ll look at how Velez brought his skills and experience to bear on this market, how Nubank was founded in 2013, and how the team brought a Californian rather than Brazilian vibe to their first office on — no joke — California Street, in a neighborhood called Brooklin in the city of São Paulo.

The makings of an entrepreneur

The idea of being his own boss was ingrained in Velez from his earliest days in Colombia, where he grew up in an entrepreneurial family, with a father who owned a button factory. “I heard from my dad over and over again that you need to start your own company,” Velez said.

But years would pass and Velez still had no idea what he wanted to do. To “kill time,” and also to surround himself with entrepreneurial energy, Velez attended Stanford University — partially financed by the sale of some livestock — and then worked as an analyst at Goldman Sachs and Morgan Stanley before switching to venture capital at General Atlantic and Sequoia.


https://ift.tt/eA8V8J How contrarian hires and a pitch deck started Nubank’s $30 billion fintech empire https://ift.tt/3zjWc2B

One woman’s drive to make a neobank as magical as Disney

As we mentioned in part 1 of this EC-1, David Velez had two key co-founding roles he needed to fill to get started building Nubank. For one, he needed a CTO to lead the engineering side of the business, as Velez didn’t have an engineering background.

Edward Wible, an American computer science graduate who spent most of his career in private equity, would take that responsibility. He didn’t bring years of coding experience, but he had qualities that Velez considered more important: A strong belief in the potential of the product and an equally intense commitment to working on it.

Given the occasionally hostile reaction of most incumbent banks to their customers in Brazil, Nubank’s starkly contrasting openness and transparency has garnered a huge following.

That left an even more important role to fill — one that was much harder to define. This other co-founder would need to blend knowledge of the Brazilian market and local savvy with expertise in banking, all while embodying a Silicon Valley ethos of focusing on customers. This person would also have to work in São Paulo for minimal wages out of a small office with just one bathroom, all in the belief that their equity (both stock and sweat) would one day be worth it.

Velez would eventually stumble upon Cristina Junqueira, who was qualified to do all this, and much, much more.

“Once someone said I was the glue of the operation, and that someone else was the brains. And I said, ‘No, I’m the glue and the brains, and I bet my brain is even better than his,”’ Junqueira said.

Junqueira didn’t just lead Nubank’s drive into the Brazilian market, she also upended age-old notions of what it means to be a 21st-century bank. Her inspiration was nothing short of Disney, and her mission was to create a bank as popular as the magical kingdom itself.

A bank. As popular as Disney. Sounds like a fairy tale, frankly.

Raised to be a doer

Unlike her co-founders Velez and Wible, Junqueira grew up in Nubank’s home market of Brazil. The eldest of four sisters, she remembers her parents — both dentists — always assiduously working to maintain their practice.

Their work ethic trickled down, but so did responsibility. As the oldest at home, she was forced to grow up quickly and take on responsibilities from an early age. “I remember being 11 years old and doing grocery shopping for the month,” she said. “I did everything very young.”


https://ift.tt/eA8V8J One woman’s drive to make a neobank as magical as Disney https://ift.tt/3glGuwk

How Nubank’s CX strategy made it one of the most loved digital banks

As we saw in parts 1 and 2 of this EC-1, by mid-2013, Nubank CEO David Velez had most of what he needed to get started. He’d brought on two co-founders, assembled ambitious engineering and operations teams, raised $2 million in seed funding from Sequoia and Kaszek, rented a tiny office in São Paulo, and was armed with a mission to deliver the kind of banking services that customers in a market as large and lucrative as Brazil’s should expect.

Despite being named Nubank, however, the startup couldn’t actually be a bank: Brazil’s laws made it illegal at the time for a foreigner-run company to operate a bank. That restriction required the team to develop an inventive product strategy to find a foothold in the market while they waited for a license directly from the country’s president.

Nubank was so adamant about differentiating itself from other banks that it chose Barney purple for its brand color and first credit card.

Nubank therefore pursued a credit card as its first offering, but it had to race against a clock counting quickly down to zero. At the time, Brazil didn’t have ownership restrictions on this product segment like it did with banking, but new rules were coming into force in just a few months in May 2014 that would block a company like Nubank from launching.

The company needed to execute rapidly over the next eight months if it wanted to be grandfathered into the existing regulations. The speed of operations was frantic to say the least, and the company would go on to work even faster, ultimately propelling itself into the stratosphere of fintech startups.

Full faith in credit

It’s easy to assume that the name Nubank refers to “new bank,” but that’s not really what the founders were going for. The word “nu” in Portuguese means “naked,” and Velez and his team wanted the name to reflect their vision: To build a 21st-Century bank without any of the shackles imposed by the traditional banks in Brazil.

The team wanted to offer services to as many people as possible, as there is a huge wealth gap in Brazil, where the minimum wage is around $200 a month.

Launching with just a credit card was both a strategic and practical business decision. Credit cards were widely used in the country, and everyone understood how they worked. Additionally, you could only use credit cards to shop online in Brazil, because debit cards weren’t accepted.


https://ift.tt/eA8V8J How Nubank’s CX strategy made it one of the most loved digital banks https://ift.tt/3cCijY3

Which Nubank will own the financial revolution?

Nubank’s first office, on California Street in the Brooklin neighborhood of São Paulo, makes for a great beginning to the company’s story. It wasn’t a Silicon Valley garage, but this tiny, one-bathroom rented house, where 30 people worked insane hours to push out the company’s debut credit card, lends just as well to an image of entrepreneurial spirit and drive.

As Nubank continues to make international waves, more and more VC investors are taking a look at the Brazilian ecosystem and could potentially fund other upstarts in the years to come.

But as Nubank’s story continued, the team eventually had to move out of that early office, and the next several offices, too. Eventually Nubank had to relocate to an eight-story building in São Paulo, which houses a large part of the company’s now 3,000-person team.

The startup reached decacorn status in far less than a decade, and it is growing faster than ever. When I interviewed CEO David Velez back in January to discuss Nubank’s $400 million Series G, he said, “We’ve gone from 12 million customers in 2019 to 34 million solely based on word of mouth.” By September last year, the company was onboarding 41,000 new customers per day.

In the five months since our interview, Nubank has managed to rope in a whopping 6 million customers to reach 40 million. It’s now valued at $30 billion.

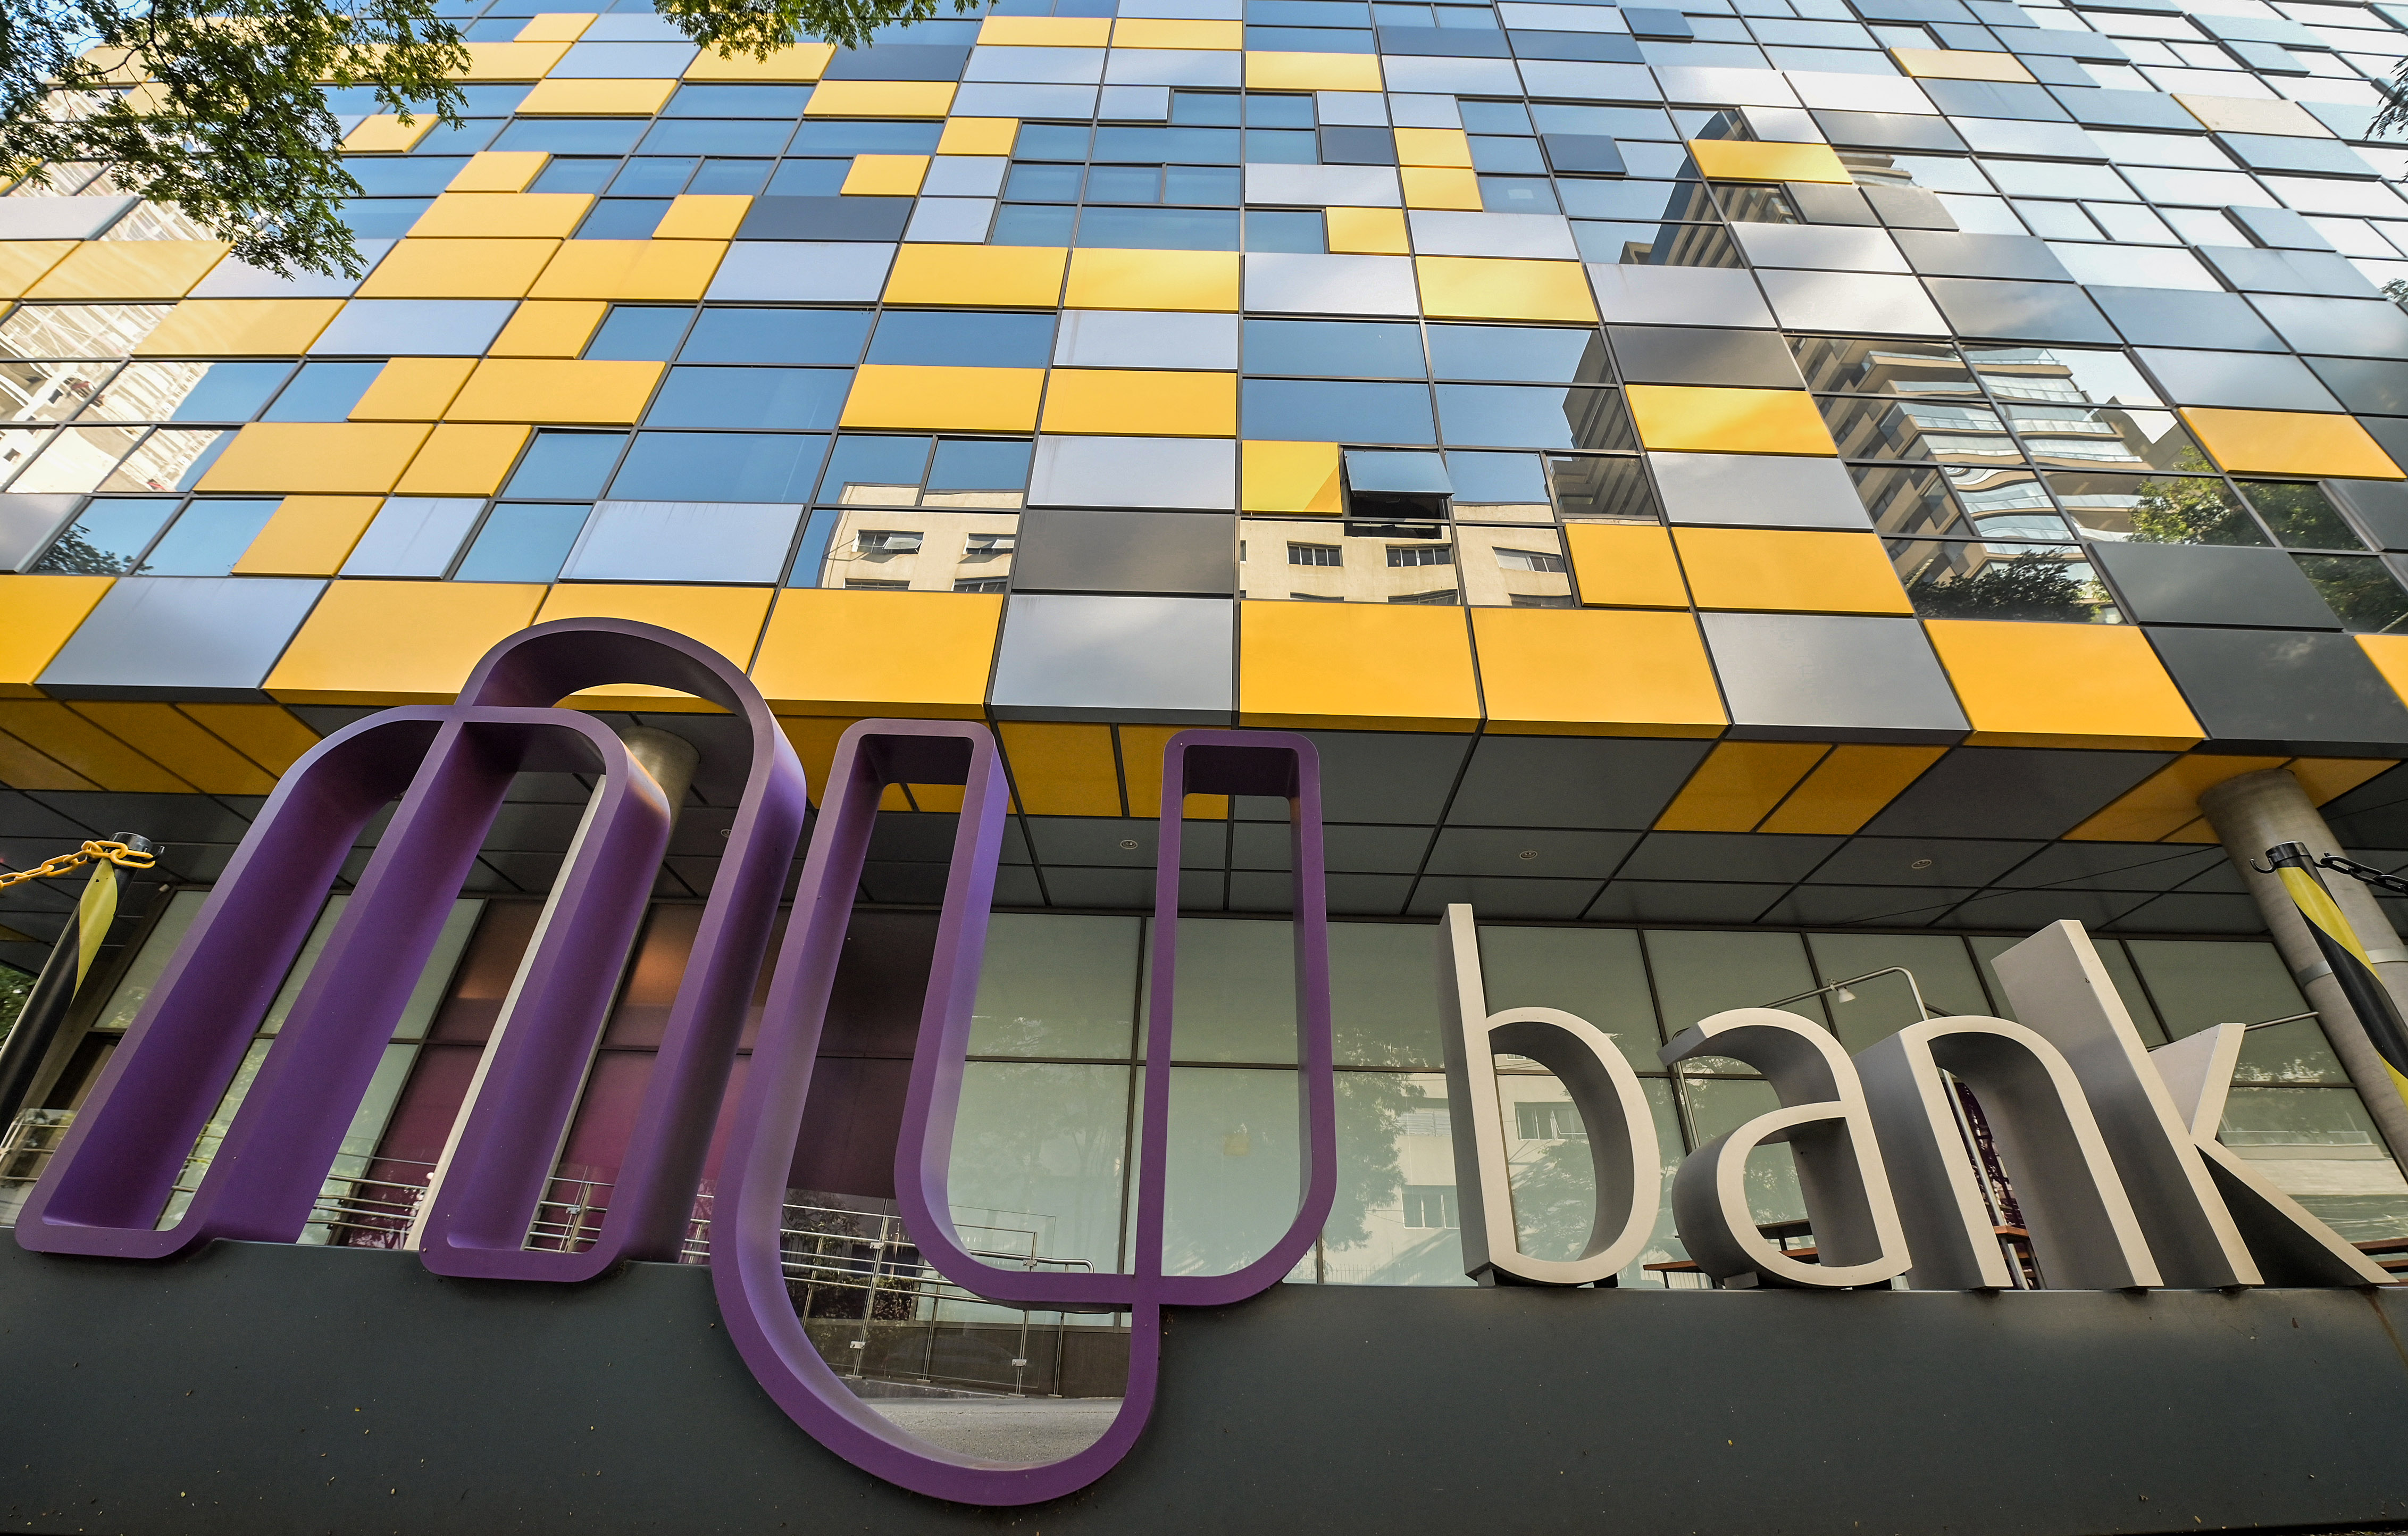
Nubank’s present day headquarters in São Paulo, Brazil. Image Credits: NELSON ALMEIDA/AFP / Getty Images

Getting there hasn’t been easy. The company’s three co-founders, Velez, Edward Wible and Cristina Junqueira, had to make key strategic decisions about how to scale themselves to retain the company’s lead in the neobanking market. That lead is getting tougher to sustain every day. Nubank’s proliferating offerings and broader geographical remit has painted a massive target on its back, and a wide number of competitors have cropped up to run on the paths it pioneered.

Like most Disney films, a fairy-tale ending seems in order, but it’ll take a few more rotations of the film wheel to get to the ending.

Early mistakes and ingredients for success

For the co-founding trio, it became increasingly clear that Nubank’s growing scale demanded critical strategic decisions on how to bring order to the company.

By 2018, the company had thousands of employees, millions of customers, and they still didn’t have a head of HR. Growth until then had been somewhat unstructured. According to Junqueira, waiting so long to hire a head of HR was one of their early mistakes, because it stunted their ability to grow. “[Good] people continue to be our biggest bottleneck,” she says.


https://ift.tt/3iEr2Nm Which Nubank will own the financial revolution? https://ift.tt/2U9b7N3

Enterprise AI platform Dataiku launches managed service for smaller companies

Dataiku is going downstream with a new product today called Dataiku Online. As the name suggests, Dataiku Online is a fully managed version of Dataiku. It lets you take advantage of the data science platform without going through a complicated setup process that involves a system administrator and your own infrastructure.

If you’re not familiar with Dataiku, the platform lets you turn raw data into advanced analytics, run some data visualization tasks, create data-backed dashboards and train machine learning models. In particular, Dataiku can be used by data scientists, but also business analysts and less technical people.

The company has been mostly focused on big enterprise clients. Right now, Dataiku has more than 400 customers, such as Unilever, Schlumberger, GE, BNP Paribas, Cisco, Merck and NXP Semiconductors.

There are two ways to use Dataiku. You can install the software solution on your own, own-premise servers. You can also run it on a cloud instance. With Dataiku Online, the startup offers a third option and takes care of setup and infrastructure for you.

“Customers using Dataiku Online get all the same features that our on-premises and cloud instances provide, so everything from data preparation and visualization to advanced data analytics and machine learning capabilities,” co-founder and CEO Florian Douetteau said. “We’re really focused on getting startups and SMBs on the platform — there’s a perception that small or early-stage companies don’t have the resources or technical expertise to get value from AI projects, but that’s simply not true. Even small teams that lack data scientists or specialty ML engineers can use our platform to do a lot of the technical heavy lifting, so they can focus on actually operationalizing AI in their business.”

Customers using Dataiku Online can take advantage of Dataiku’s pre-built connectors. For instance, you can connect your Dataiku instance with a cloud data warehouse, such as Snowflake Data Cloud, Amazon Redshift and Google BigQuery. You can also connect to a SQL database (MySQL, PostgreSQL…), or you can just run it on CSV files stored on Amazon S3.

And if you’re just getting started and you have to work on data ingestion, Dataiku works well with popular data ingestion services. “A typical stack for our Dataiku Online Customers involves leveraging data ingestion tools like FiveTran, Stitch or Alooma, that sync to a cloud data warehouse like Google BigQuery, Amazon Redshift or Snowflake. Dataiku fits nicely within their modern data stacks,” Douetteau said.

Dataiku Online is a nice offering to get started with Dataiku. High-growth startups might start with Dataiku Online as they tend to be short on staff and want to be up and running as quickly as possible. But as you become bigger, you could imagine switching to a cloud or on-premise installation of Dataiku. Employees can keep using the same platform as the company scales.


https://ift.tt/eA8V8J Enterprise AI platform Dataiku launches managed service for smaller companies https://ift.tt/3gAJKmv

Anrok raises $4.3M to solve sales tax for SaaS companies

It’s easier than ever to build a product and sell it around the United States, or the world. But if you want to do so without incurring the wrath of any particular state, or nation-state, you’d best have your tax matters in order. This is why Stripe’s news last week that it has built tax-focused tooling to help its customers manage their state bills mattered.

But for SaaS companies, things can be more complicated from a tax perspective. That’s what Anrok, a startup working to build sales tax software for SaaS firms, told TechCrunch.

The company’s CEO, Michelle Valentine, said that modern software companies need specialized help. And her startup is announcing a $4.3 million fundraise today to back its efforts. The capital event was led by Seqouia and Index, the latter firm a place where Valentine used to work.

Anrok delivers its service via an API, and charges based on the total dollar value of sales that it helps a customer manage. Its percentage-fee falls with volume, and you can’t pay more than 0.19% of managed revenue, so it’s pretty cheap regardless, given how strong software gross margins tend to be.

The Anrok founding team: Michelle Valentine, and Kannan Goundan. Via the company.

Valentine said that there are three things that make SaaS tax issues more complex than other products. The first deals with addresses. Software companies have to pay sales tax where customers are located, and often only have partial information. Anrok will help with that problem. The CEO also said that variable SaaS billing makes charging the right amount of tax an interesting issue, and that states have tax laws specifically aimed at the software market that must be navigated.

So, a more mass-market solution might not be the best fit for SaaS companies looking to avoid both trouble with states and the work of handling tax matters themselves.

It’s not hard to see why Anrok was able to raise capital. The company is early-stage with its first customers onboarded, so it’s not posting the sort of revenue growth that investors covet at the later stages. What then were its more fetching attributes? From our perspective, on-demand pricing and a simply gigantic market.

Sure, Anrok is serving SaaS businesses, but it’s doing so using what could be described as a post-SaaS business model; on-demand, or usage-based pricing is an increasingly popular way to charge for software products today, putting Anrok closer to the cutting edge in business-model terms. And the company’s market is essentially every software business out there. That’s a lot of TAM to carve into, something that investors love to see.


https://ift.tt/3cER7Iy Anrok raises $4.3M to solve sales tax for SaaS companies https://ift.tt/2TveWvC

blogger better Headline Animator